FX Daily Strategy: Asia, Oct 15
Core CPI uncomfortable for Fed, risks extending EUR/USD towards its major 1.10~ level
Warsh watched for any pointers
EUR/AUD toying with big support into employment data
UK GDP seen correcting, trend has held up better than feared so far
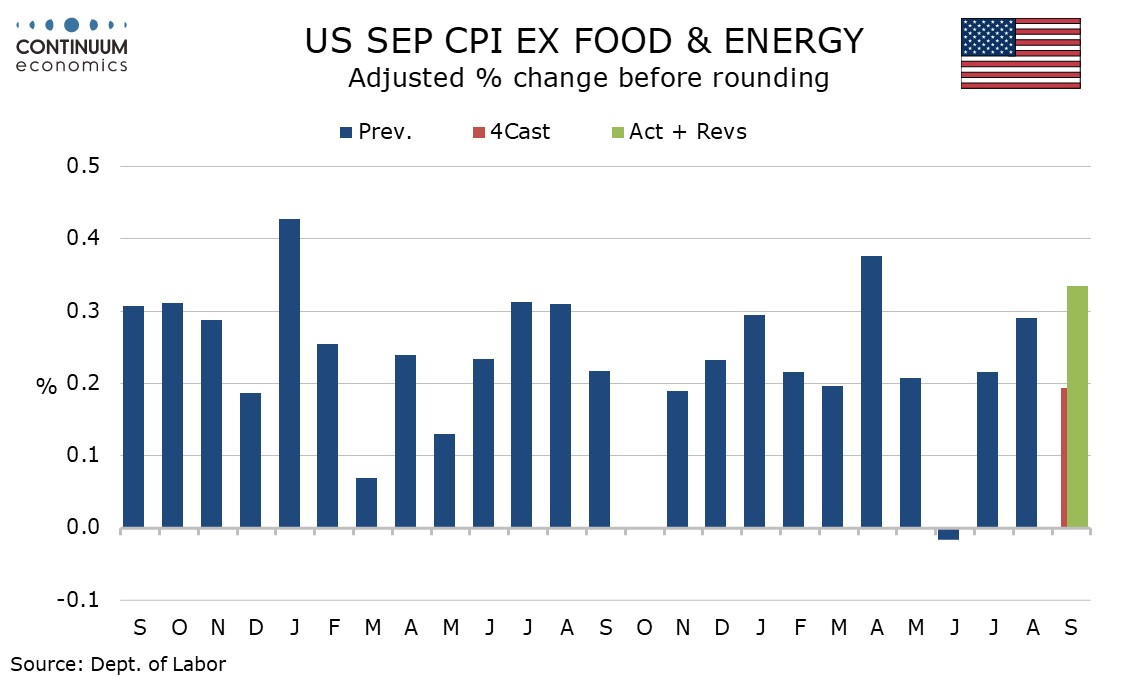
As suspected, upside risks to the core US CPI print did indeed materialise at 0.335%, with firmness also seen in the details (see here). It’s certainly a provocative report and leaves the Fed with some awkward decisions now. The preference clearly had been to wait Dec but now Oct is back in the game, and that reflected in market pricing that has moved back out to 50-50.
This puts Fed chair Warsh’s comments from Thailand a big near-term focal point, although of course that depends if Warsh is in Jackson-Hole-guidance mode, or in a no forward guidance mood, as to whether it proves informative or not.
Adding to some of the dynamic, euro spreads are at present tending to perform in high beta fashion, with the OAT-bund spread also moving back out wider after a brief respite with the renewed upside pressure on US yields.
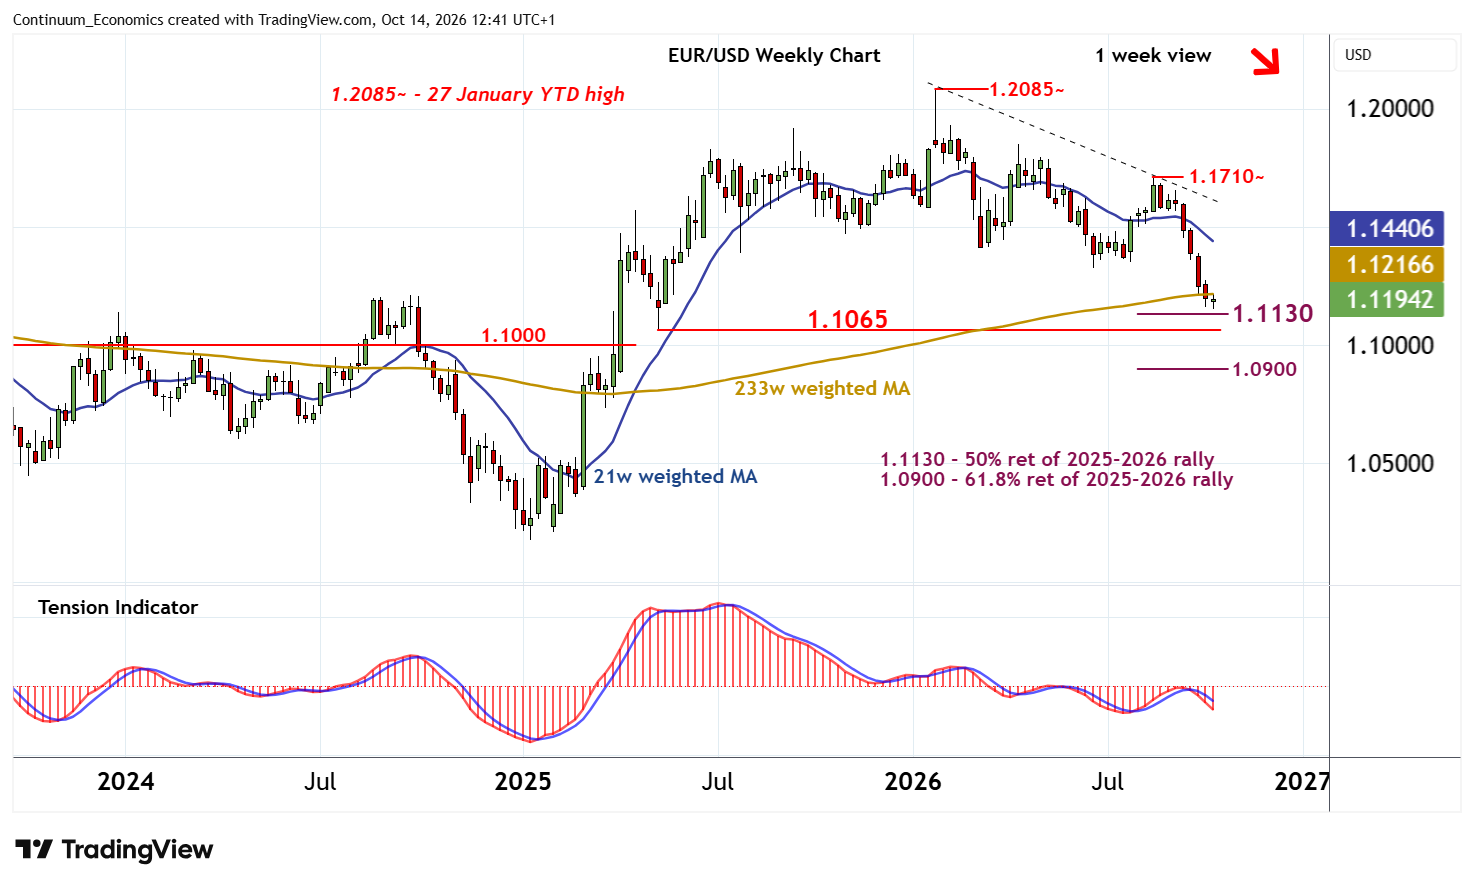
EUR/USD’s break below 1.130 fib if held could therefore be at risk of another fast run on to complete the full run down to the major 1.10~ zone. While the market had got very short euros, it was by no means tapped out (positioning as of last week was still only half of more major extremes).
Lower yielders also suffering, even those with the better fiscal characteristics. USD/SEK in particular notably posted an outside day reversal bar, suggesting a look at least to the recent highs, with similar for USD/CHF.
While the dollar story is dominating broadly, and the Thursday evening (Friday Asia) Warsh appearance is now critical, there is some interest on the calendar prior.
Australia sees the important employment release, with the market looking for a 20k trend gain and the unemployment rate sticking at 4.6%.
EUR/AUD broke (marginally) the previously highlighted major 1.6~ mark although it still has the June23 lows of 1.5845~ as the ‘range stretch’ of recent years before it is clearly marking a more notable breakdown.

The UK has Aug monthly GDP with consensus for a 0.1% correction from the above-trend 0.4% lift last month, leaving the 3m/3m and yr/yr trends flat to firmer. Trends have proved surprisingly resilient thus far. Sterling’s outperformance has been somewhat stymied by the dollar driven action and so some intraday catch up with cable’s break below 1.32, bringing the 1.3140 low into frame. EUR/GBP low is still a little shy of 0.84 (to 0.8375 fib) lower targets though and they could still be tagged if any dollar extension now has a little more room to run on the euro side.
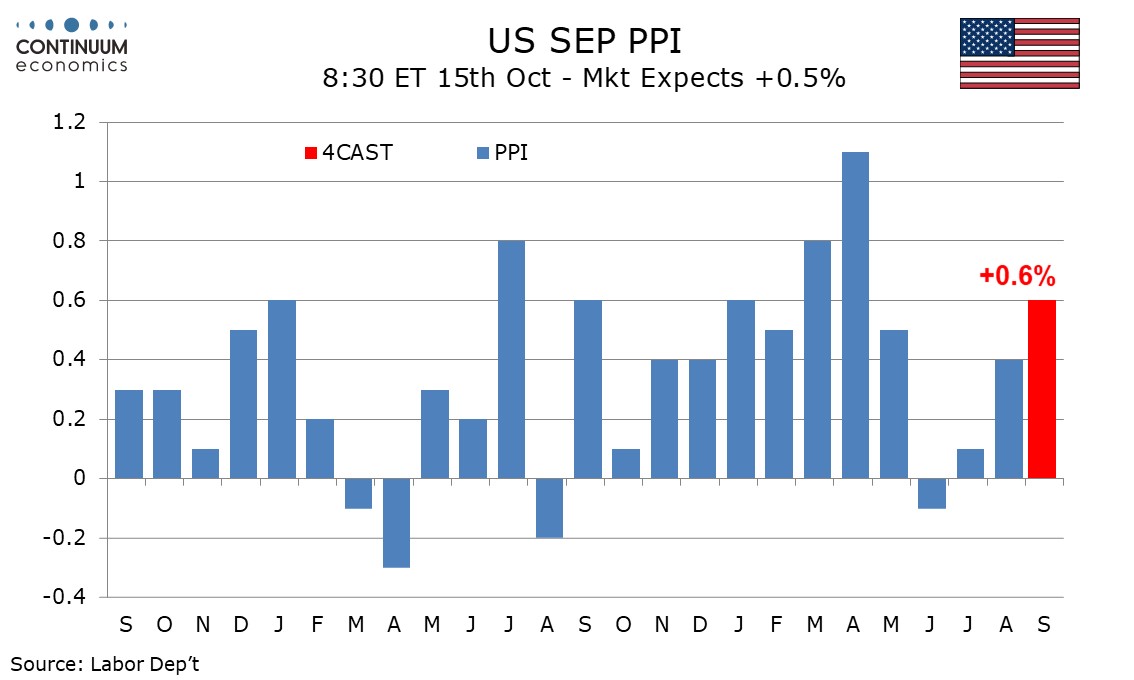
There are some notable releases in the US too, including September’s PPI, expected to increase by 0.6%, and with a 0.3% increase ex food and energy. At the same time, we expect a weak September retail sales report, up 0.1% overall and 0.4% ex autos, but down by 0.1% ex autos and gasoline. Weekly initial claims, as well as October’s manufacturing surveys from the Philly Fed and Empire State are also due. August business inventories follow, where existing data imply a rise of 0.4%. Fed’s Hammack will speak again on Thursday.