FX Daily Strategy: Asia, Nov 12
Dollar extends as market adjusted to shift in inflation scenarios
Low yielders especially pressured again, while risk holds up
UK GDP seen robust, continues to defy challenging backdrop
One day in and the market is more fully digesting the macro narrative shift that the latest CPI print delivered. One 0.3% core is an accident, three in a row becomes a trend and one that, in Fed’s Goolsbee’s words, is bordering disturbing. That can change of course, and oil is simultaneously on a retreat from the pre-election highs, but for now it is a re-anchoring of the market’s macro assessment and the risk scenarios for inflation and policy that accompany it.
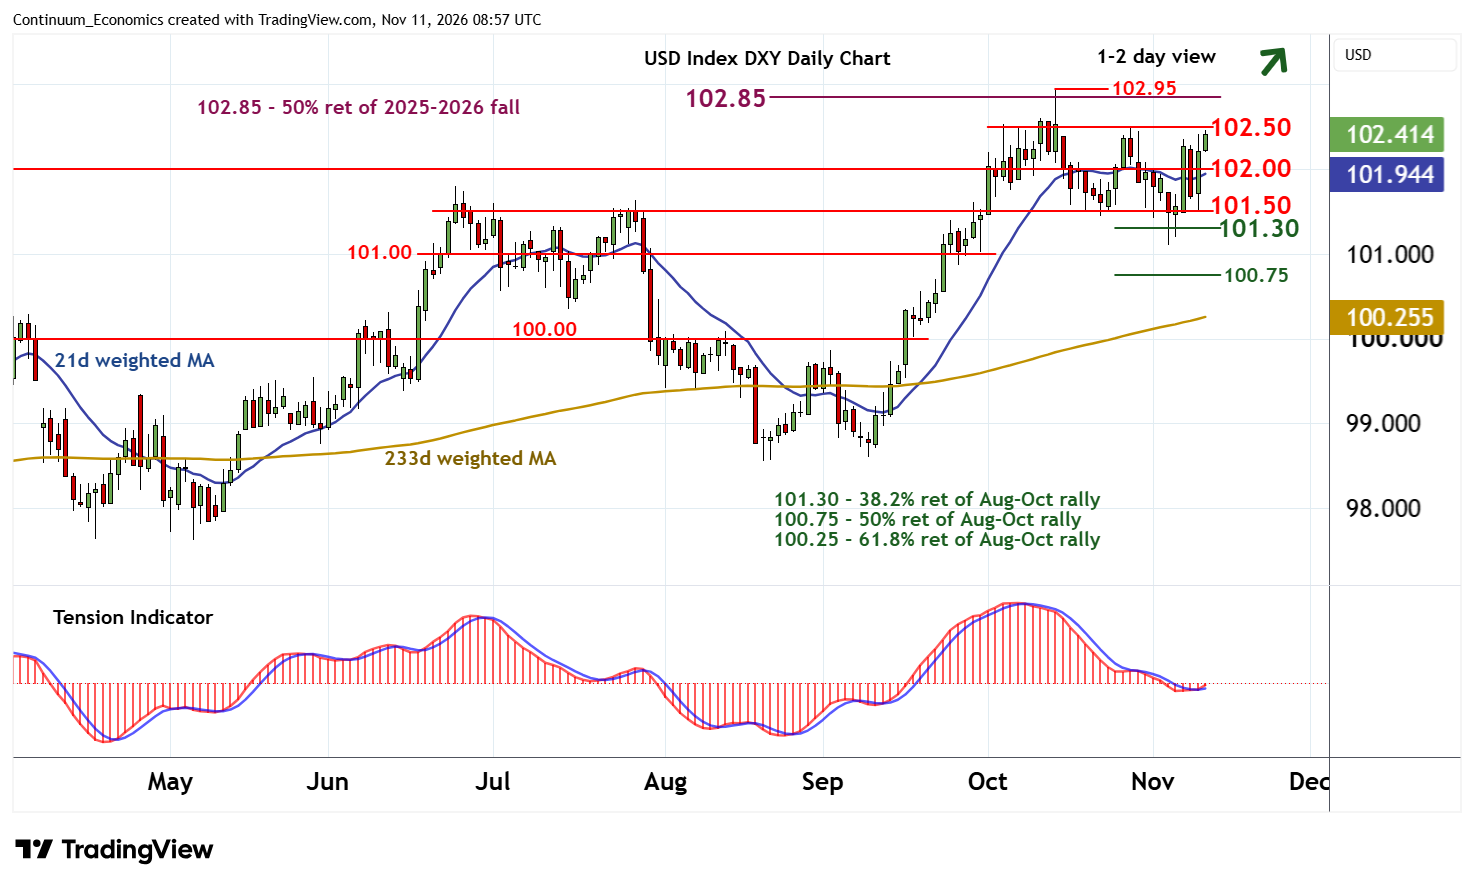
Renewed breadth of recent inflation strength has concerned Fed speakers as much as extent. Fed opinions regarding the extent of current policy tightness (less than thought), the responsiveness (or lack of) of tech investment and its inflation pressures to higher interest rates, and pressure for the real economy versus energy have all shifted or at least been moved onto less secure ground.
Stretched though dollar positioning may be, at least on some counters (euro and of course more severely the antipodeans more than many), it is hard to see the dollar not attempting to continue to test the limits of higher on the back of this.
USD/JPY has to contend with nerviness of until recently receded MoF concerns, but with the recent breakout (and the market long yen), the pair does look set to extend into 160 next to see if that surfaces a deeper layer of medium-term offers.
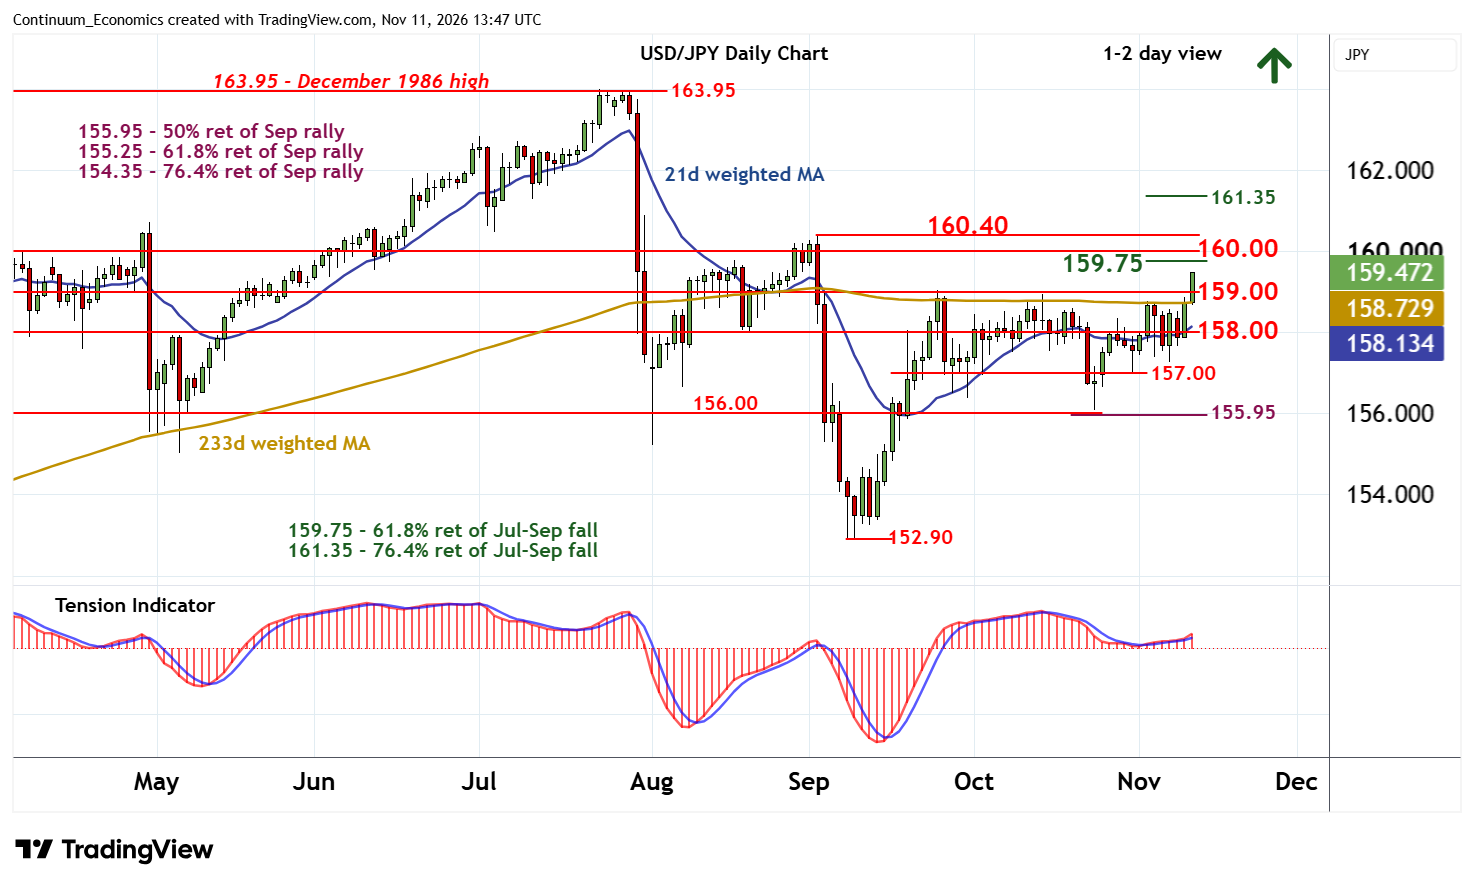
Low yielders generally are back to suffering (CHF and SEK), at least while and so long as risk sentiment manages to avoid negative feedback and tech remains on its attempted correction rather than extending into a deeper top formation.
For the time being, this looks set to dominate trade. Thursday does see UK GDP data where ongoing resilience is also a narrative and where the BoE is not without its concerned citizens either - Lombardelli this week seeing risks that persistent inflation will crystallise and drive higher rates, while NIESR is pessimistic regarding the prospects for long-term inflation over 4%.
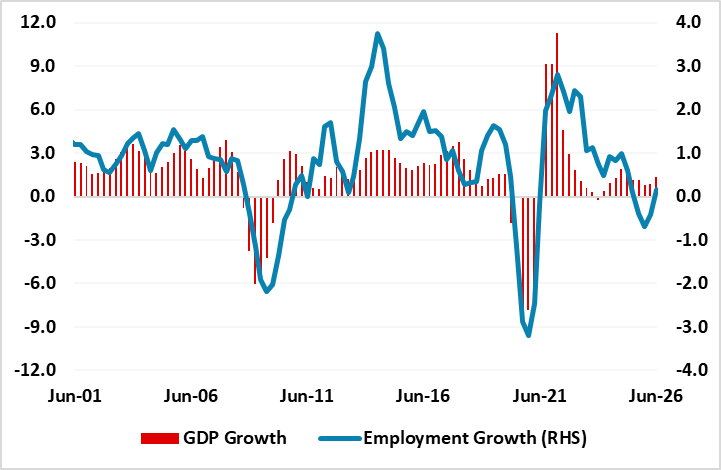
We expect quarter on quarter growth to have increased by 0.7%, in line with estimates produced by the BoE in last week’s Monetary Policy Report. If Sep manages anything more than flat, it will see an upside surprise. Q4 is projected to slow notably from what is a high pace, but projections have so far proved premature. The market still is already running ahead of the BoE shift to an extent though and cable is, along with other pairs, struggling to avoid gravity with 1.3200 - 1.3250 as pullback support.
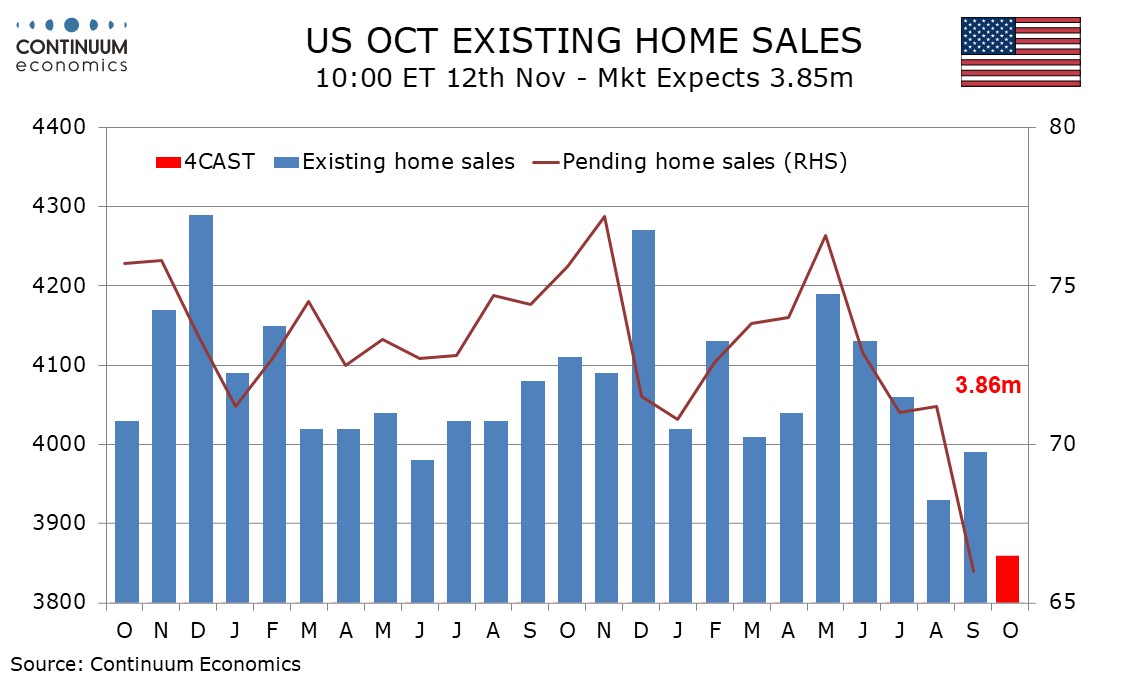
In the US, we expect October existing home sales to fall by 3.3% to 3.86m. Weekly initial claims are also due. PPI data on Friday is more material to the current focus though.