FX Daily Strategy: Asia, Nov 10
Risk attempts to bounce on oil and tech lift, but outlook still unclear
Back from the noise, EUR/USD not far from 1.12 pivot, and DXY stuck in a 1 figure range
Positioning does remain heavily defensive, especially on yen risk crosses
US CPI offers some normality. On-consensus results anticipated
An attempt at a positive start to the week, although it’s still unclear how much traction this latest risk-lift can maintain.
US crude’s decline on the back of Trump’s comment downplaying the chances of further strikes takes it back to the recent lows and key support from the Oct lows. If that gives way then the next settlement area is down at $80, late Aug lows.
NOK continues to go along with the wider USD/risk tone but if this further breakdown does happen, it still seems at risk of some unwind of its recent heavy outperformance, by virtue of it status as the oil-strength-hedge trade.
For tech stocks, it’s still a decent attempted bounce now attempting from the post-election selloff, even with Nvidia’s issues, and a move that accelerated back into the prior range - though there is more ground to make yet before this would mark a break of the recent downtrend and so a more convincing turn.
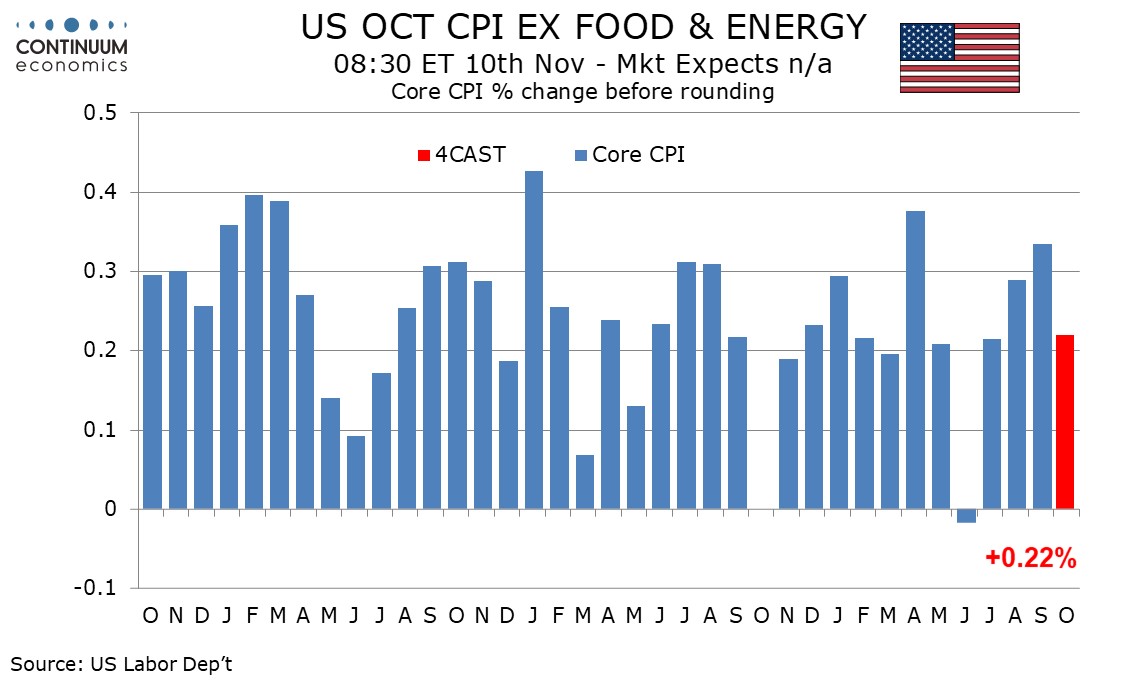
Focus today switches back to more normal business with US CPI. We expect more subdued CPI in October after two straight disappointing 0.3% gains in the core rate, with October’s core rate seen at 0.2%, 0.22% before rounding. Gasoline prices have seen only a marginal rise on the month, and we expect overall CPI to also rise by 0.2%, though at 0.24% before rounding.
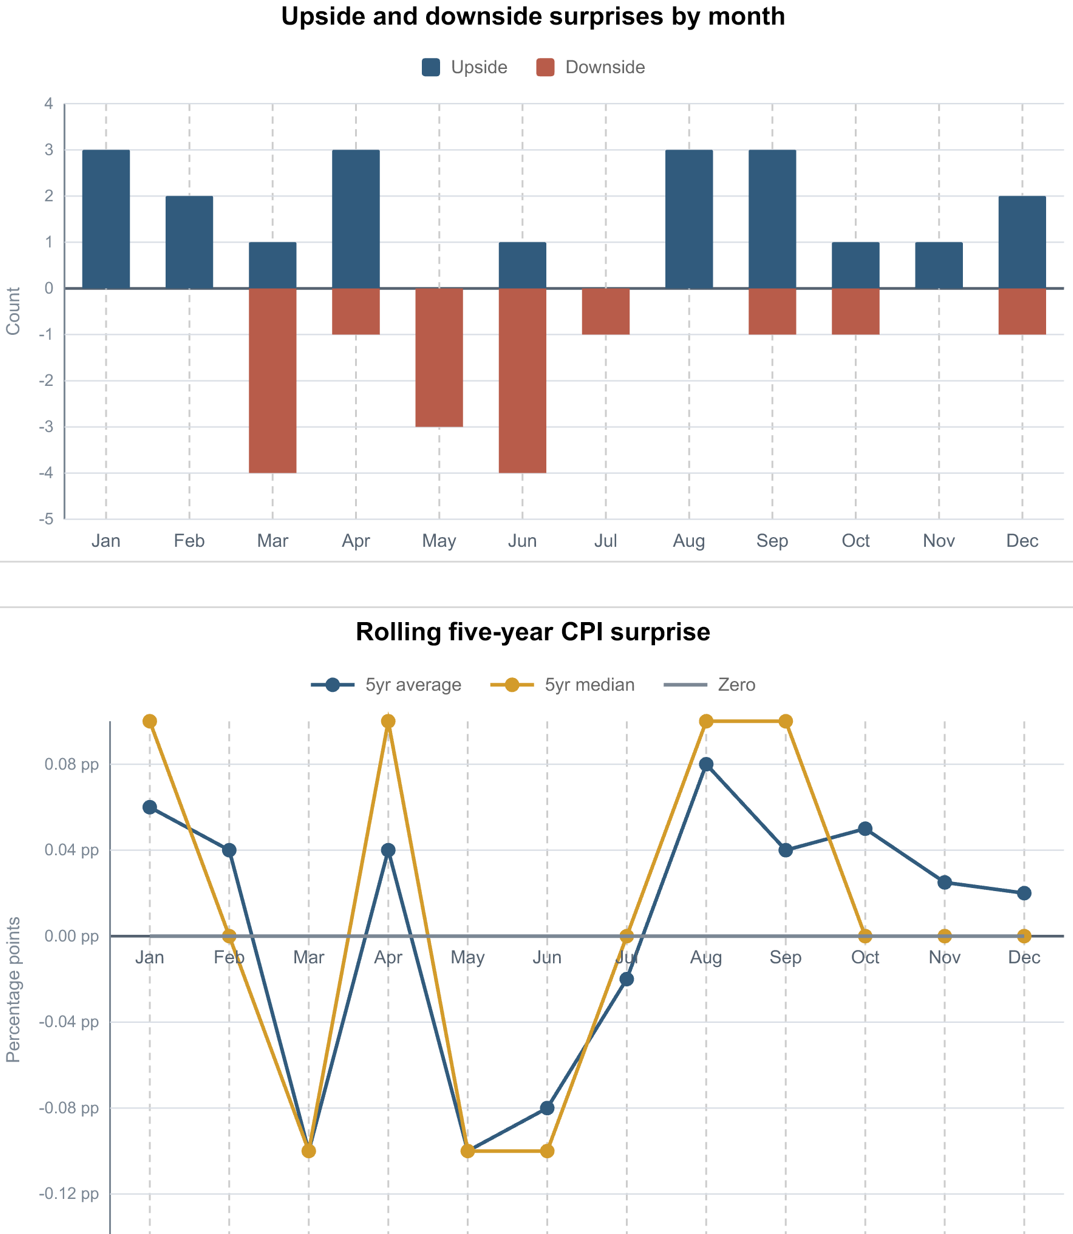
In terms of seasonals and cross-correlation with headline, this month is also a more ‘neutral’ month than the last two, so risks of upside surprise seem appreciably lower, with on consensus results more typical.
The market still has Dec hike odds up at 80% or so. An as-expected result should still leave the current status quo in place especially after robust payrolls, everything else constant, though perhaps still chances of a touch of 'relief' and sell the fact for the dollar, given recent upside surprises.
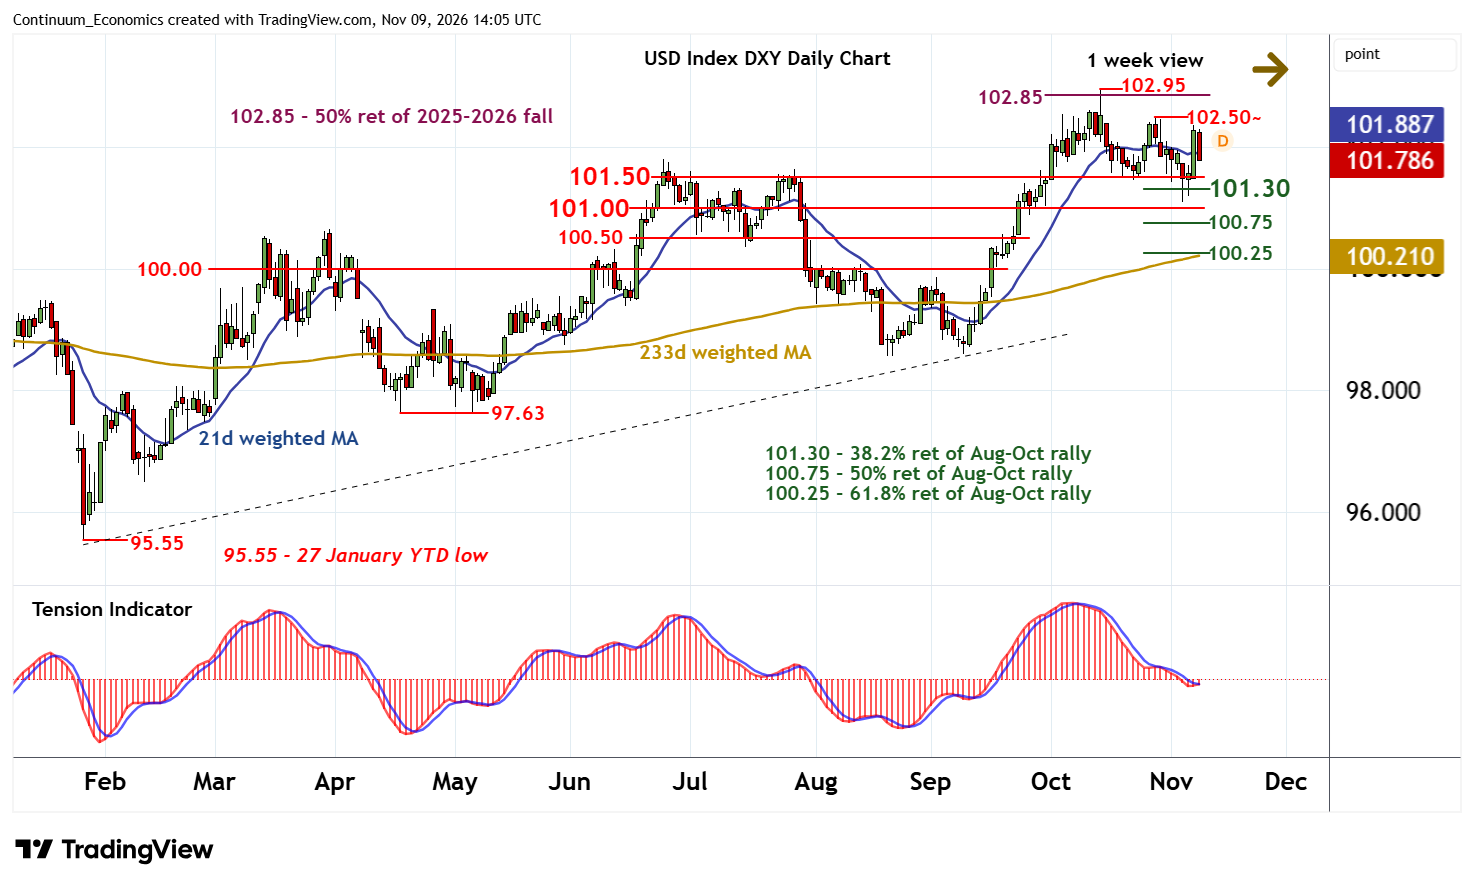
Current dollar trade though remains more broadly consolidative and indecisive. DXY trade remains caught in a one figure of so range and with little clear immediate direction looking for an impetus for the next break. Sentiment reflects that with a split between dip buying and strength selling biases.
Likewise, even with some of the recent gyrations, through the noise EUR/USD has emerged not far from the 1.12 pivot that has been around for a while and so action remains inconclusive.
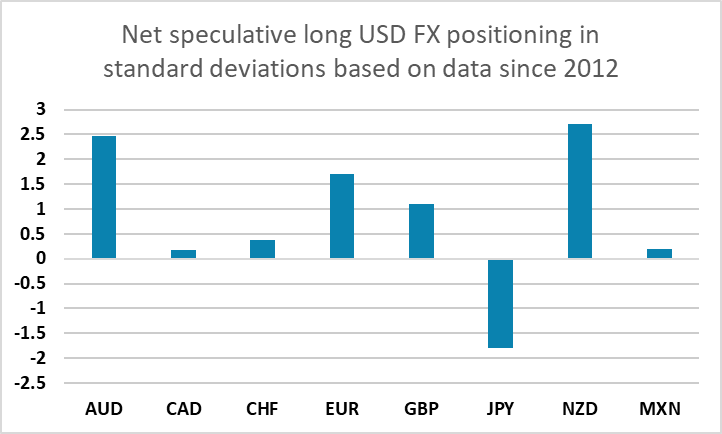
Wider positioning remains one consideration and does highlight counter-trend risks if unexpected positive developments emerge. Classic risk-JPY positioning is at extreme risk-off defensive levels while euro is getting within 10% of the 2015 short extremes. This does need current developments on geopolitics and the tech shake out to align though for squeeze risks to kick in.