Could blow out in French spreads, CDS, catch up with the euro? (EUR/GBP flows)
Recent action in OAT-bund spreads continues to extend, yet to fully come onto the FX mkt radar
EUR-GBP CDS spread widening the fastest since 2017
EUR/GBP could extend the resistance test failure to range lows if relative risk re-pricing starts to impact narrative, sentiment
The market loves a narrative, better still a fall guy. It doesn’t seem that long ago sterling was floundering with Starmer on the way out and Burnham’s high showing in the polls recast as the second-coming of Trotsky. Jokes aside, the political story and in particular deteriorating fiscal weakness, instability and vulnerability enmeshed around it increasingly matters for FX. The recent action in OATs, highlighted in the bond outlook (here), may increasingly become a material factor for euro.
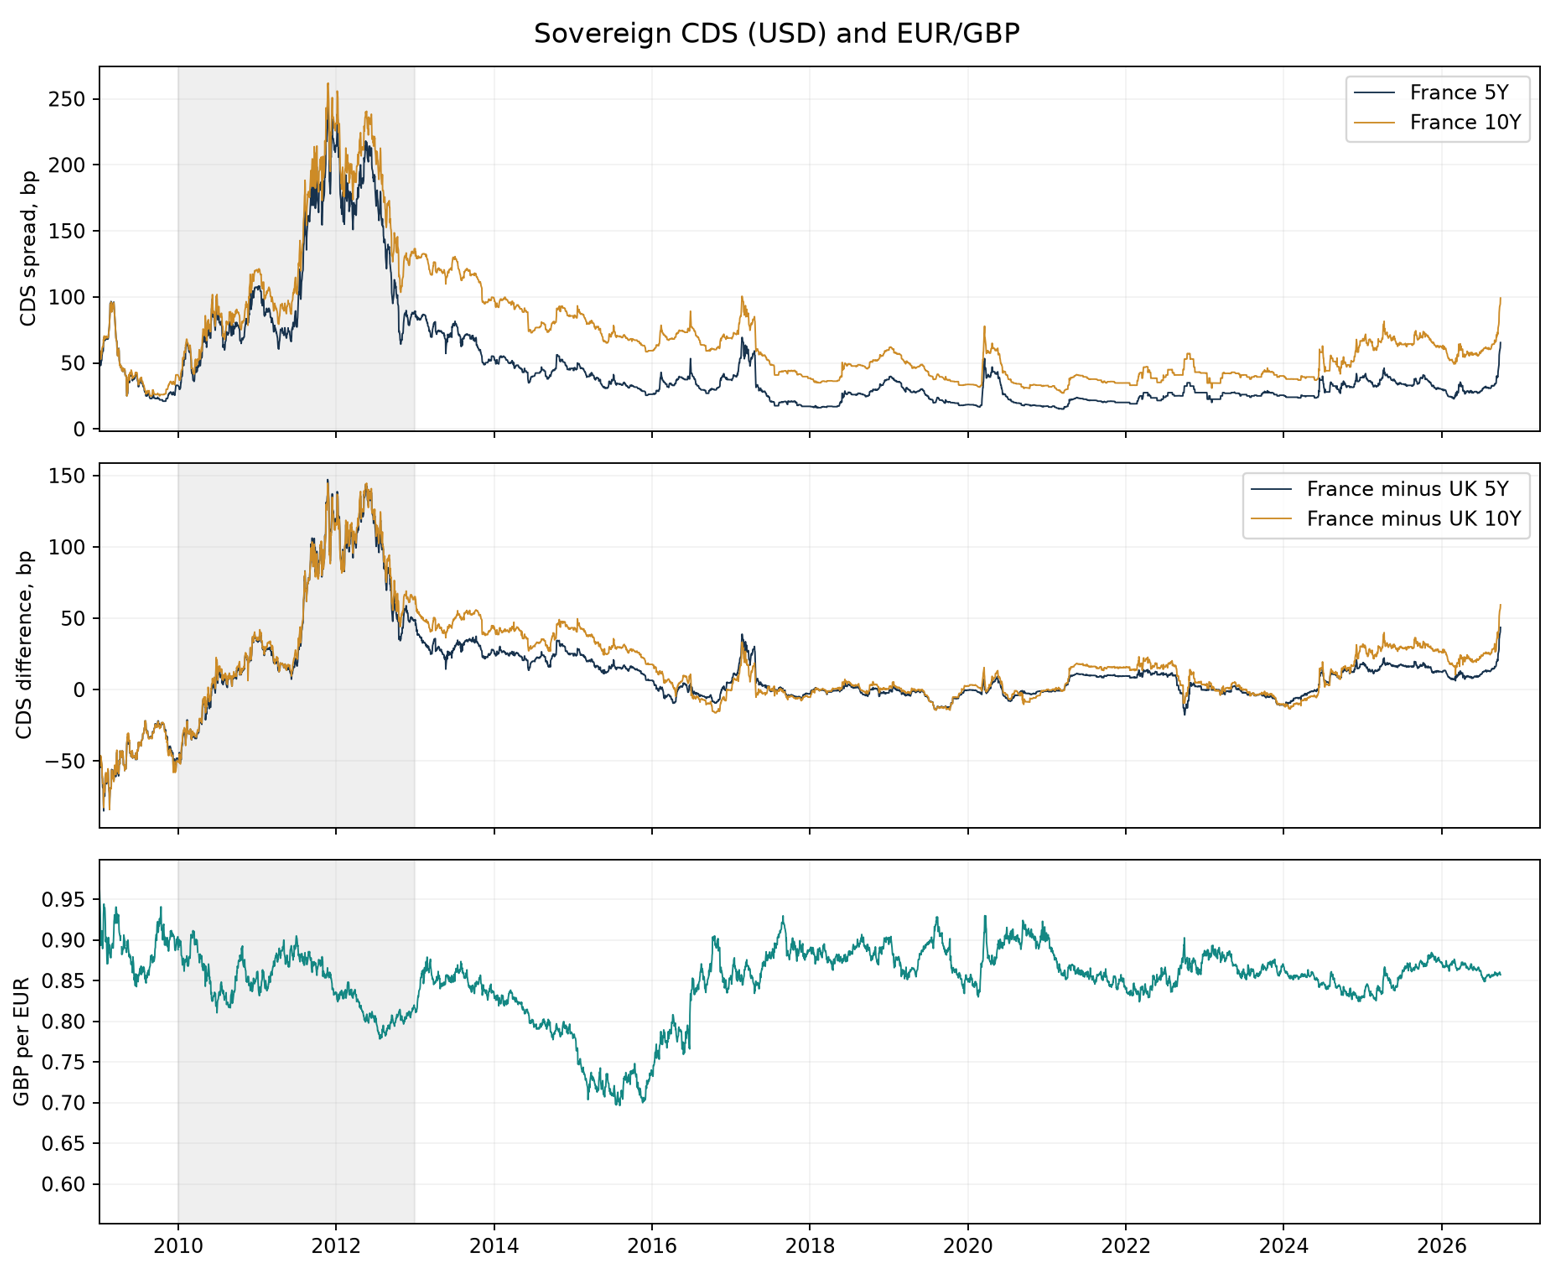
Indeed, the charge in OAT-bund spreads, taking out the old 80-90bp ceiling and rapidly accelerating into the 120s, starts to take it into the low foothills of the euro crisis period. It doesn’t take much in terms of panic, speculative momentum, liquidity and flow issues for a “Truss Budget” like episode to blow up from here, with moves out to 150bp~. The UK LDI-driven forced selling was a specific amplifier in the UK’s disorderly move example, but that doesn’t mean that short-term imbalances can’t accelerate quickly regardless, as the recent action has shown. Response to current government efforts (if seen wholly inadequate, or worse run into political deadlock) could be an aggravating factor if they fail to impress.
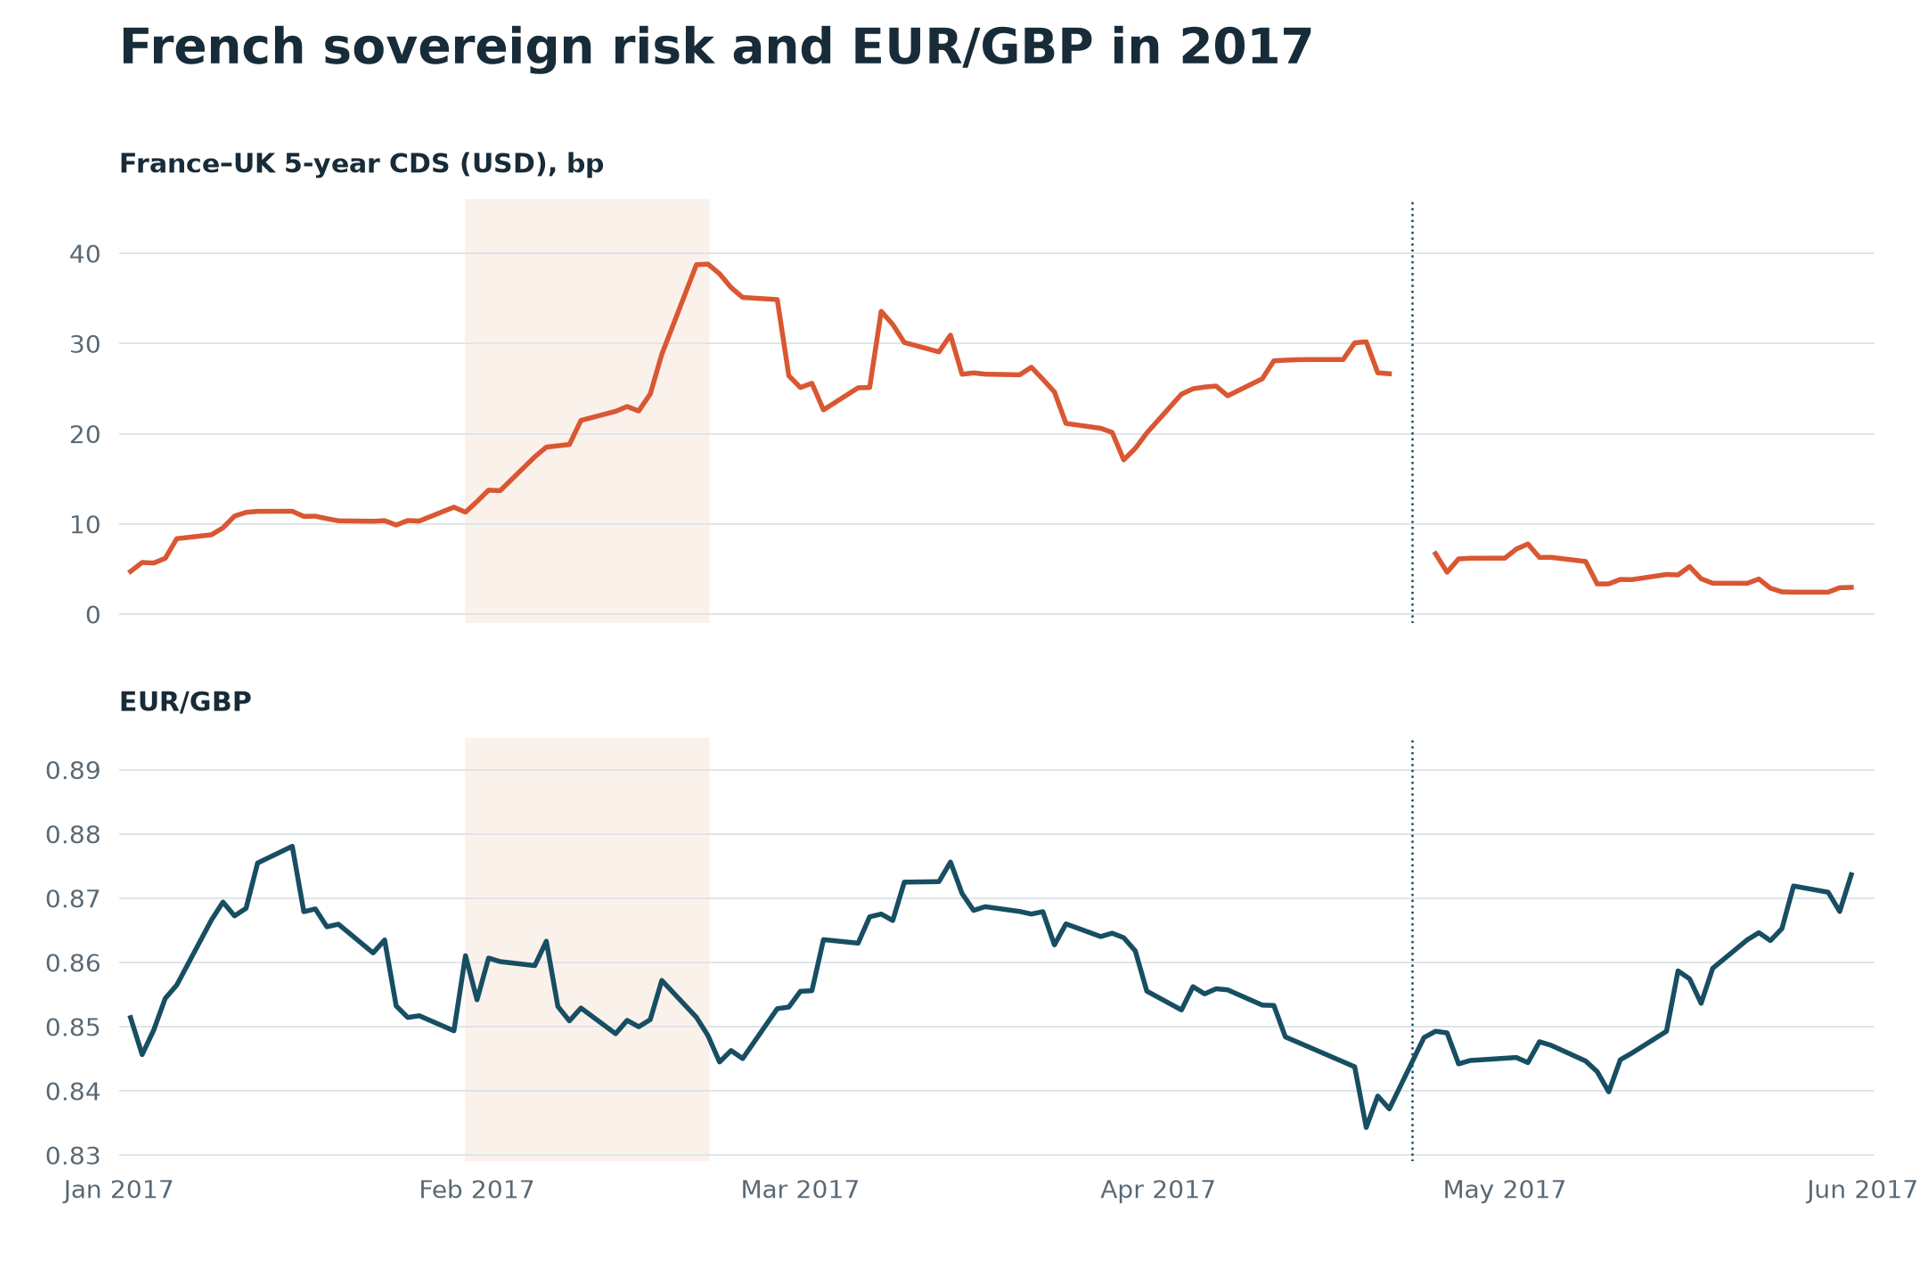
The CDS picture is less extreme than back in the euro crisis of course but still marked. France’s 5yr CDS premium over UK has pushed out almost 30bp, from 14bp to 44bp (on a common USD base), the widest gap since January 2013, with the pace of widening just exceeding the surge into February 2017. This remains well below the peaks reached in 2011, but stands as a substantial post-crisis move.
To an extent, this is an intra-euro story rather than necessarily currency-wide, at this point, but impact both in terms of sentiment, narrative and, to an extent, flows can be seen. Japan has historically been a large overweight French buyer and a reactive seller, though it has already significantly lightened its exposure in the 2024-5 period.
The 2017 precedent is instructive more generally. As French election concerns intensified then, EUR/GBP dropped from prior highs of 0.88 to April lows around 0.84 alongside the relative CDS move, although UK politics contributed and much of it subsequently reversed, with the step-jump relief move then following the French first round.
In the current context, despite the action in the bond market, FX attention of late has been more focused elsewhere, particularly the rate cycle. On EUR/GBP, both the BoE’s slower pace of additional tightening (being a laggard in the latest rate hike round) and more generally political risk into the UK Budget have kept the cross propped.
The latter may prove to be overdone, while recent data suggests the spec market has got pretty short GBP. EUR/GBP’s failed tests of 0.86/10 also sets a more negative chart backdrop to the cross. Wider range support runs down from 0.85-0.8455 if a shift in risk pricing carries across to the FX side in coming days. EUR/USD is more oversold but the trend is still currently down with 1.20 the next major support lower.