FX Daily Strategy: Europe, Oct 15
Core CPI uncomfortable for Fed, but dollar spike reversed as bonds U-turn, equities sell
Warsh watched for any pointers
UK GDP again better than expected, as resilience continues
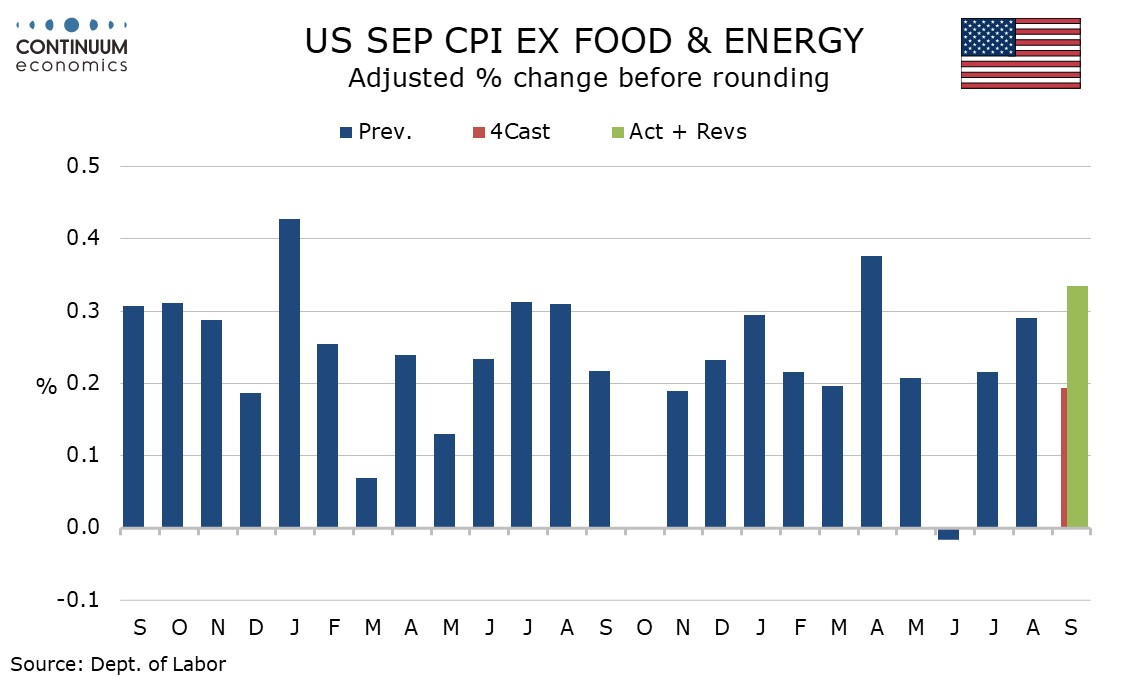
As suspected, upside risks to the core US CPI print did indeed materialise at 0.335%, with firmness also seen in the details (see here). It’s certainly a provocative report and leaves the Fed with some awkward decisions now. The preference clearly had been to wait Dec but now Oct is back in the game, and that reflected in market pricing that has moved back out to 50-50.
That said, Fed's Daly stuck to a 'hikes likely but no urgency' message, bonds found strong buyers again suggesting its reached an area of perceived better hedging value to reverse the initial sell-off and Asia saw further ongoing equity selling led again by the Kospi, all combining to make the FX data reaction a false break. These spike reversals could therefore suggest some near-term exhaustion after extended overbought dollar moves.
This puts Fed chair Warsh’s comments from Thailand a big near-term focal point, although of course that depends if Warsh is in Jackson-Hole-guidance mode, or in a no forward guidance mood, as to whether it proves informative or not.
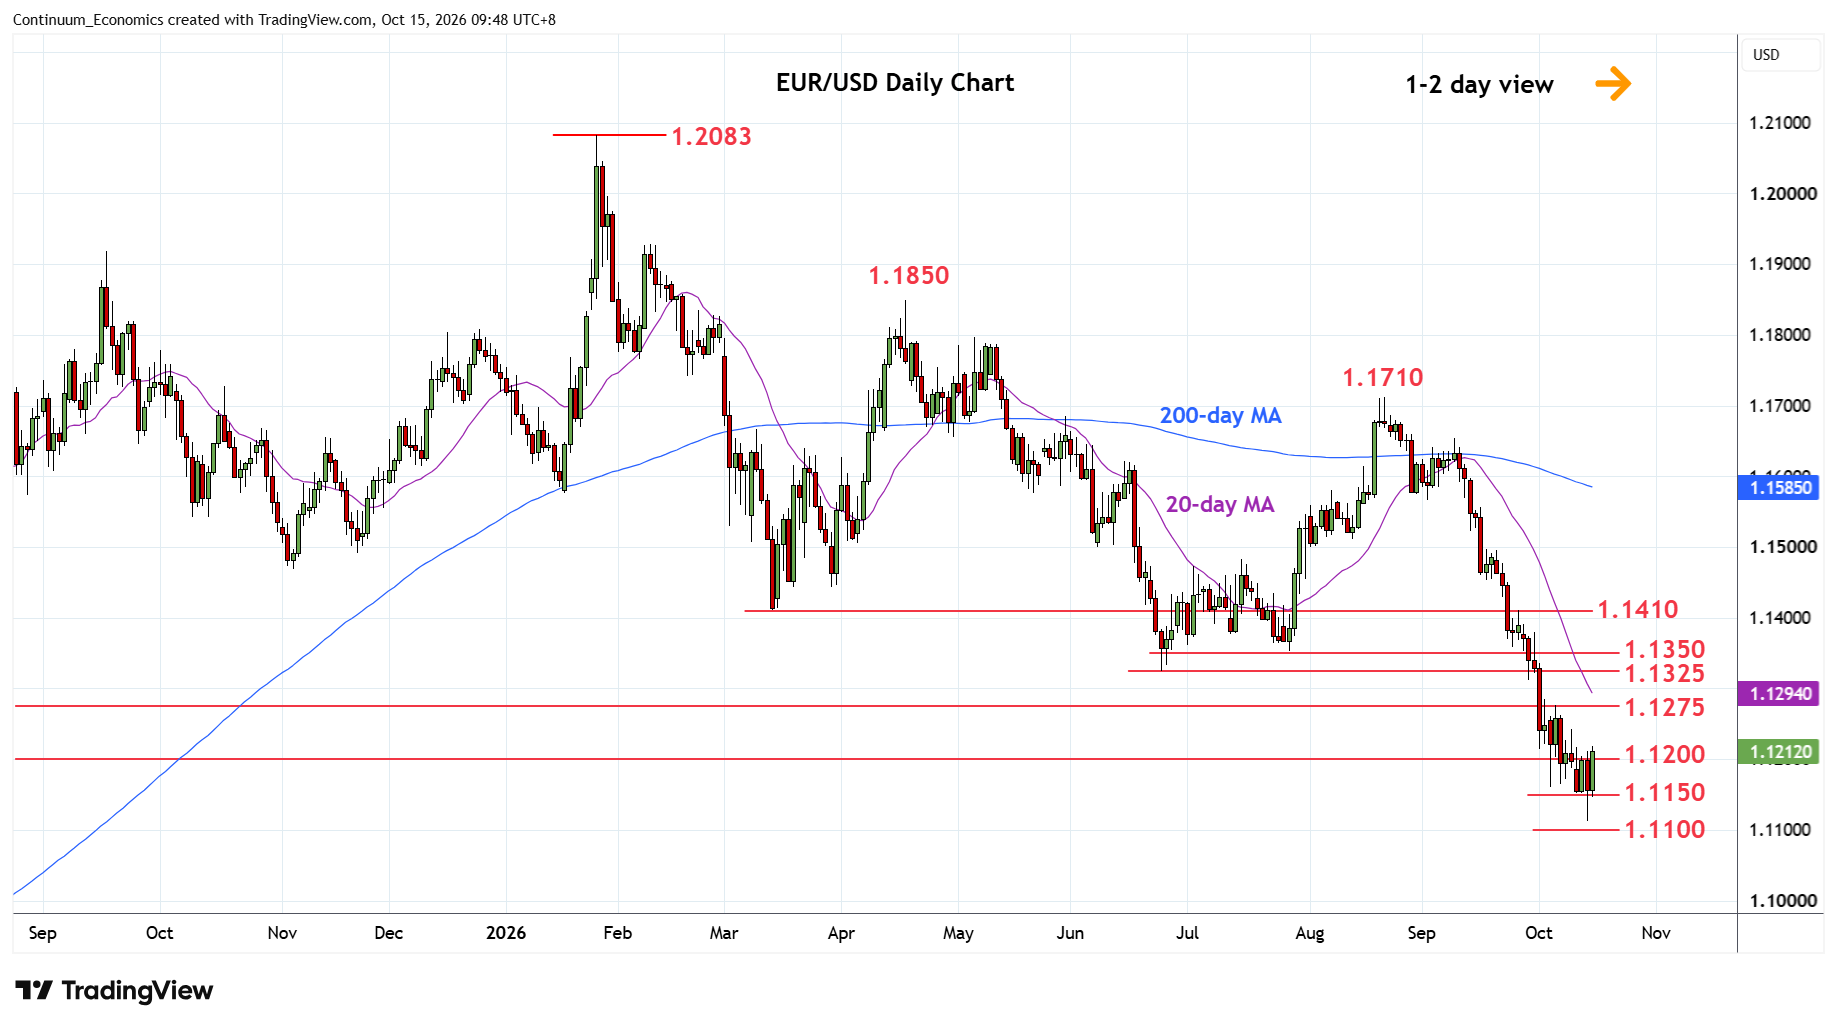
EUR/USD’s oversold stretch lower and then 1.2 regain opens room towards resistance at the 1.1250/75 area on the charts.
USD/JPY also continues to see strong supply showing on the moves into 159, and selling again overnight reinforces that heavier tone. JPY also showing better signs of some safety/hedging demand seen in the wider asset market performance. 157.50/157.00 area is support.
While the dollar story is dominating broadly, and the Thursday evening (Friday Asia) Warsh appearance is now critical, there is some interest on the calendar prior.
Australia saw the important employment release, with a strong downside surprise at -39k versus market +20k, albeit driven by part-time, additionally taking the edge off the AUD bounce.
EUR/AUD broke (marginally) the previously highlighted major 1.6~ mark although it still has the June23 lows of 1.5845~ as the ‘range stretch’ of recent years before it is clearly marking a more notable breakdown.

The UK has Aug monthly GDP meanwhile surprises to the upside again at +0.1%m/m versus market expectations for a 0.1% correction, taking the 3m/3m to 0.7% and the yr/yr to 2.1%. Data is supportive, and with the grain of the dollar-led cable bounce, although is set against a background where even the hawkish voices on the BoE are suggesting that the pace of the 4 hikes priced into the market is to be viewed with scepticism.
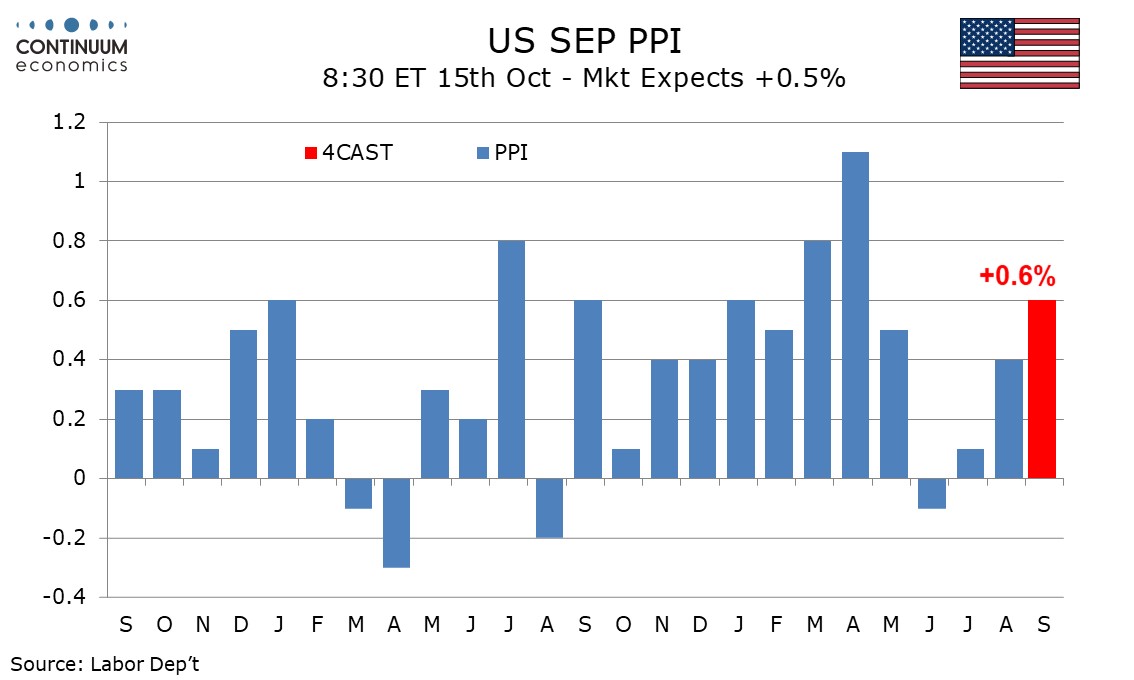
There are some notable releases in the US too, including September’s PPI, expected to increase by 0.6%, and with a 0.3% increase ex food and energy. At the same time, we expect a weak September retail sales report, up 0.1% overall and 0.4% ex autos, but down by 0.1% ex autos and gasoline. Weekly initial claims, as well as October’s manufacturing surveys from the Philly Fed and Empire State are also due. August business inventories follow, where existing data imply a rise of 0.4%. Fed’s Hammack will speak again on Thursday.