U.S. Initial Claims, September Philly Fed, August Housing Starts and Permits - More positives than negatives
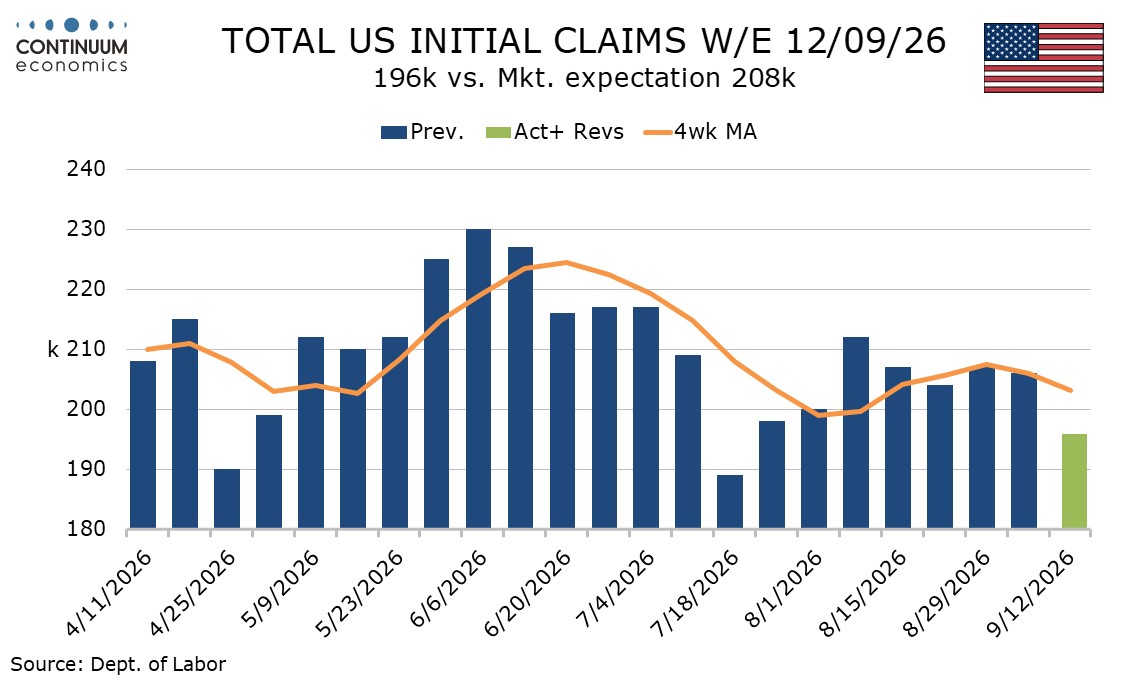
The latest data is mixed but positives outweigh the negatives. Initial claims at 196k from 206k are very low indeed and take on extra significance in that this is the survey week for September’s non-farm payroll. September’s Philly Fed manufacturing index of 37.8 is down from 47.4 but still very strong, including its price signals. Declines in August housing starts of 2.6% and permits of 2.7% are however weaker than expected and Fed tightening may bring more weakness in the housing sector going forward.
The initial claims number is the lowest since July 18 though some caution is necessary in that the week includes the Labor Day holiday, making seasonal adjustments tricky. The 4-week average of 203.25k is marginally below the 204.25k seen in the August non-farm payroll survey week.
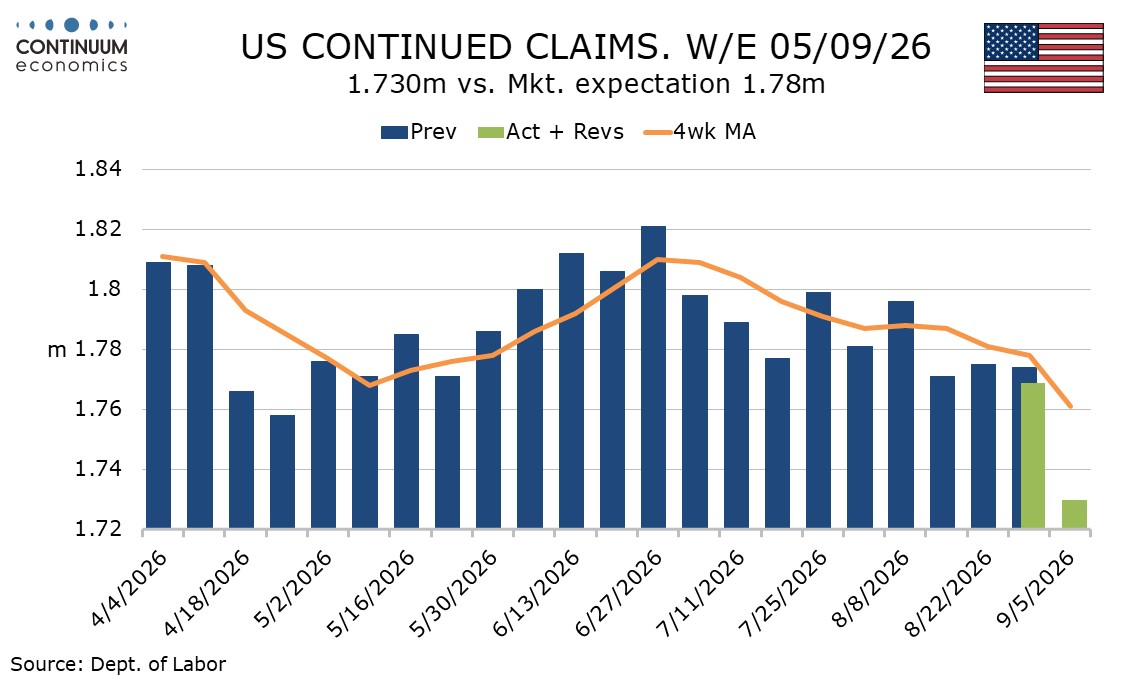
Continued claims cover the week before initial claims, and a also fell, by 39lk to 1.73m. This is the lowest level since May 2023, and suggests the unemployed are finding jobs.
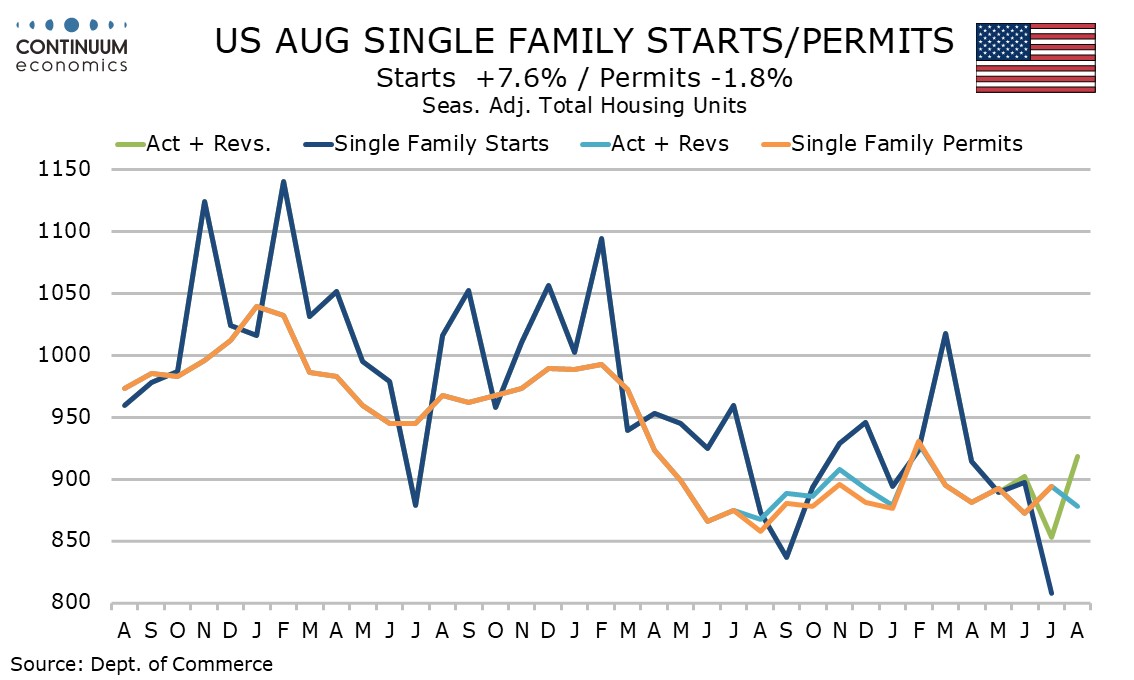
August’s 2.6% housing starts decline surprisingly extends a 9.0% July decline though single starts increased by 7.6% after a 5.4% July decline. A 21.7% fall in multiples is probably in part erratic, though is the second straight fall after a sharp bounce in June that followed a very weak May.
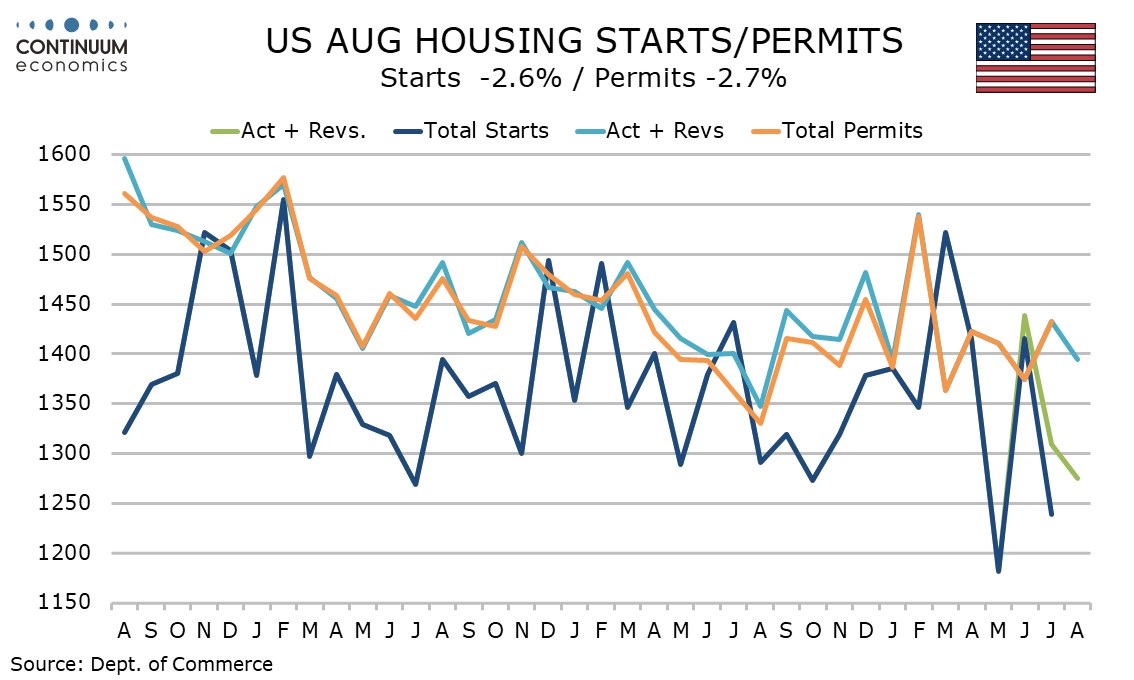
Permits with a 2.7% decline to 1.394m do not fully reverse a 4.3% July increase and both singles and multiples saw only partial corrections from July gains. Trend in permits is still fairly flat but risks going ahead are on the downside given the latest Fed tightening and potential for more.
September’s Philly Fed manufacturing index, like the Empire State index, has weakened, but unlike the Empire State Index, its level of 37.4 remains strong and does not imply weakening in indices such as the ISM or S and P manufacturing PMIs.
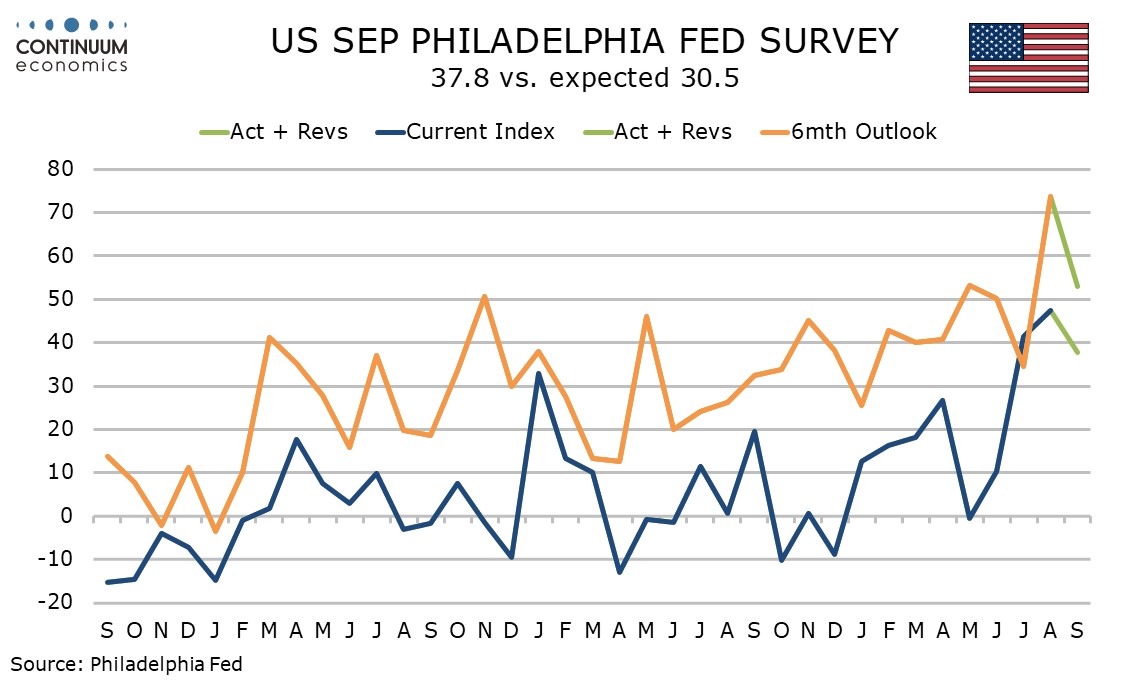
Six month expectations at 52.9 are down from 73.6 in August but up from 34.4 in July and similar to levels seen in May and June.
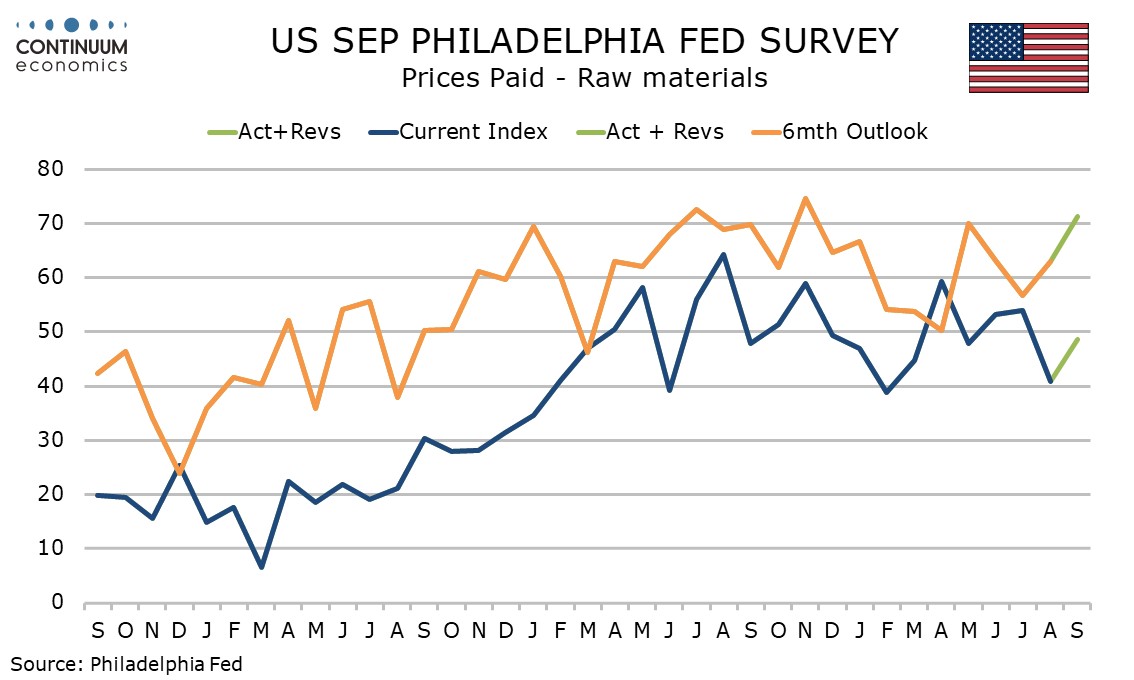
Price indices are stronger. Current month prices paid at 48.6 from 40.9 are still below July’s 53.9 but current month prices received at 71.3 from 62.9 are the highest since December 2025.
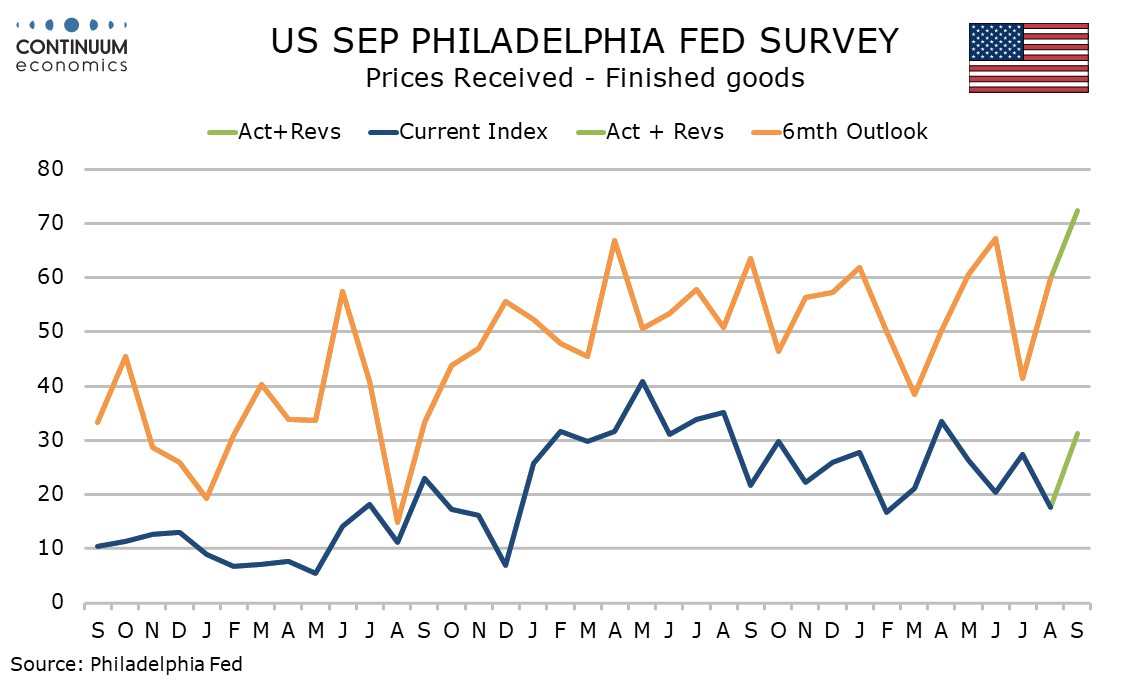
Six month expectations for prices paid rebounded to 31.3 from August’s weaker 17.7 and are at their highest since April. Six month expectations for prices received at 72.3 from 59.8 are the highest since September 1981. That is alarming.