FX Daily Strategy: N America, Oct 22
Positioning and oversold conditions obstructing euro follow through traction; downside focus switching to options protection
AUD lifted by short-covering and momentum swing towards a Nov hike pricing
JPY and CHF winning the haven battle
Focus remains news driven rather than calendar-centric
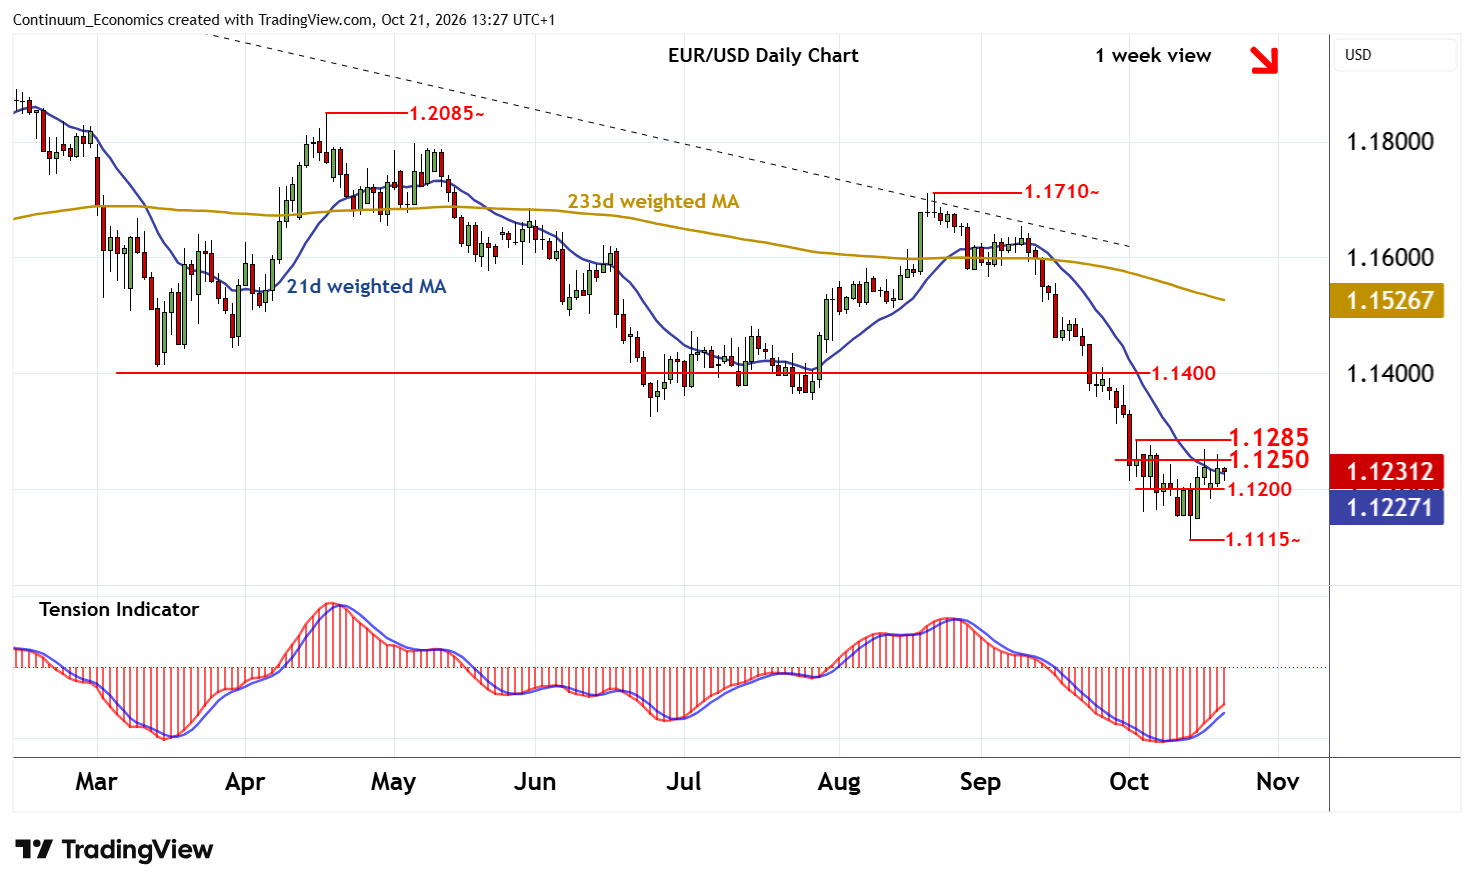
No real change from the current setup, with the euro faced with negative news flow from ongoing France-centric pressure, but positioning and stretched price action an obstacle to follow through traction, at least on EUR/USD.
That and current tech heaviness is finding better expression in the traditional JPY and CHF havens than USD too. EUR/CHF extends the retracement to close to 0.92 figure ahead of the 0.91~ May lows. EUR/JPY weighed back to the recent 176~ base ahead of much further substantial potential long-term retracement scope on a larger JPY reversal.
While big picture EUR/GBP focus is on the lower more major range downside at around 0.8, trading is tending to focus more on downside options positioning, across a number of pairs/crosses, instead rather than follow through spot action.
The cross did manage to stretch below 0.84, but is stalling at the fib just below and very oversold. Likewise, amid the headwind provided by the broadly stretched long dollar positioning, EUR/USD is not really managing much leakage beyond 1.1220 even intraday when French bonds are pressing the recent bond wides. Heavy expiries also tending to reinforce the current freeze. Indeed, Thursday actually sees very large expiries up at 1.13/05 that could also encourage the market to attempt to force a bounce.
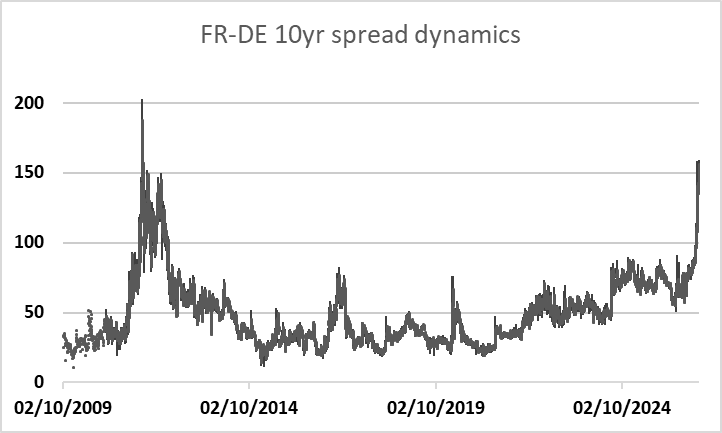
So while recent price action and historical precedent of these ‘logarithmic’ spread moves provides valid concerns that the next pullback could then set up the next leg accelerate to 200bp for FR-DE10s - with wider potential ‘reverse contagion’ before it forces a more decisive policy response - for now the current positioning standoff remains in place.
France today is seeing 10s drive through the recent peaks on to 167/8bp, while Belgium (also in the semi-core club) is also seeing spreads to bunds breakout higher above 100bp and the ‘shape’ of the recent spread chart doesn’t look great.
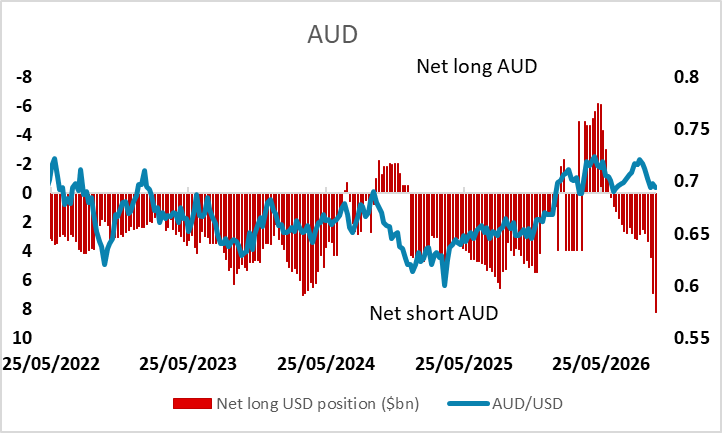
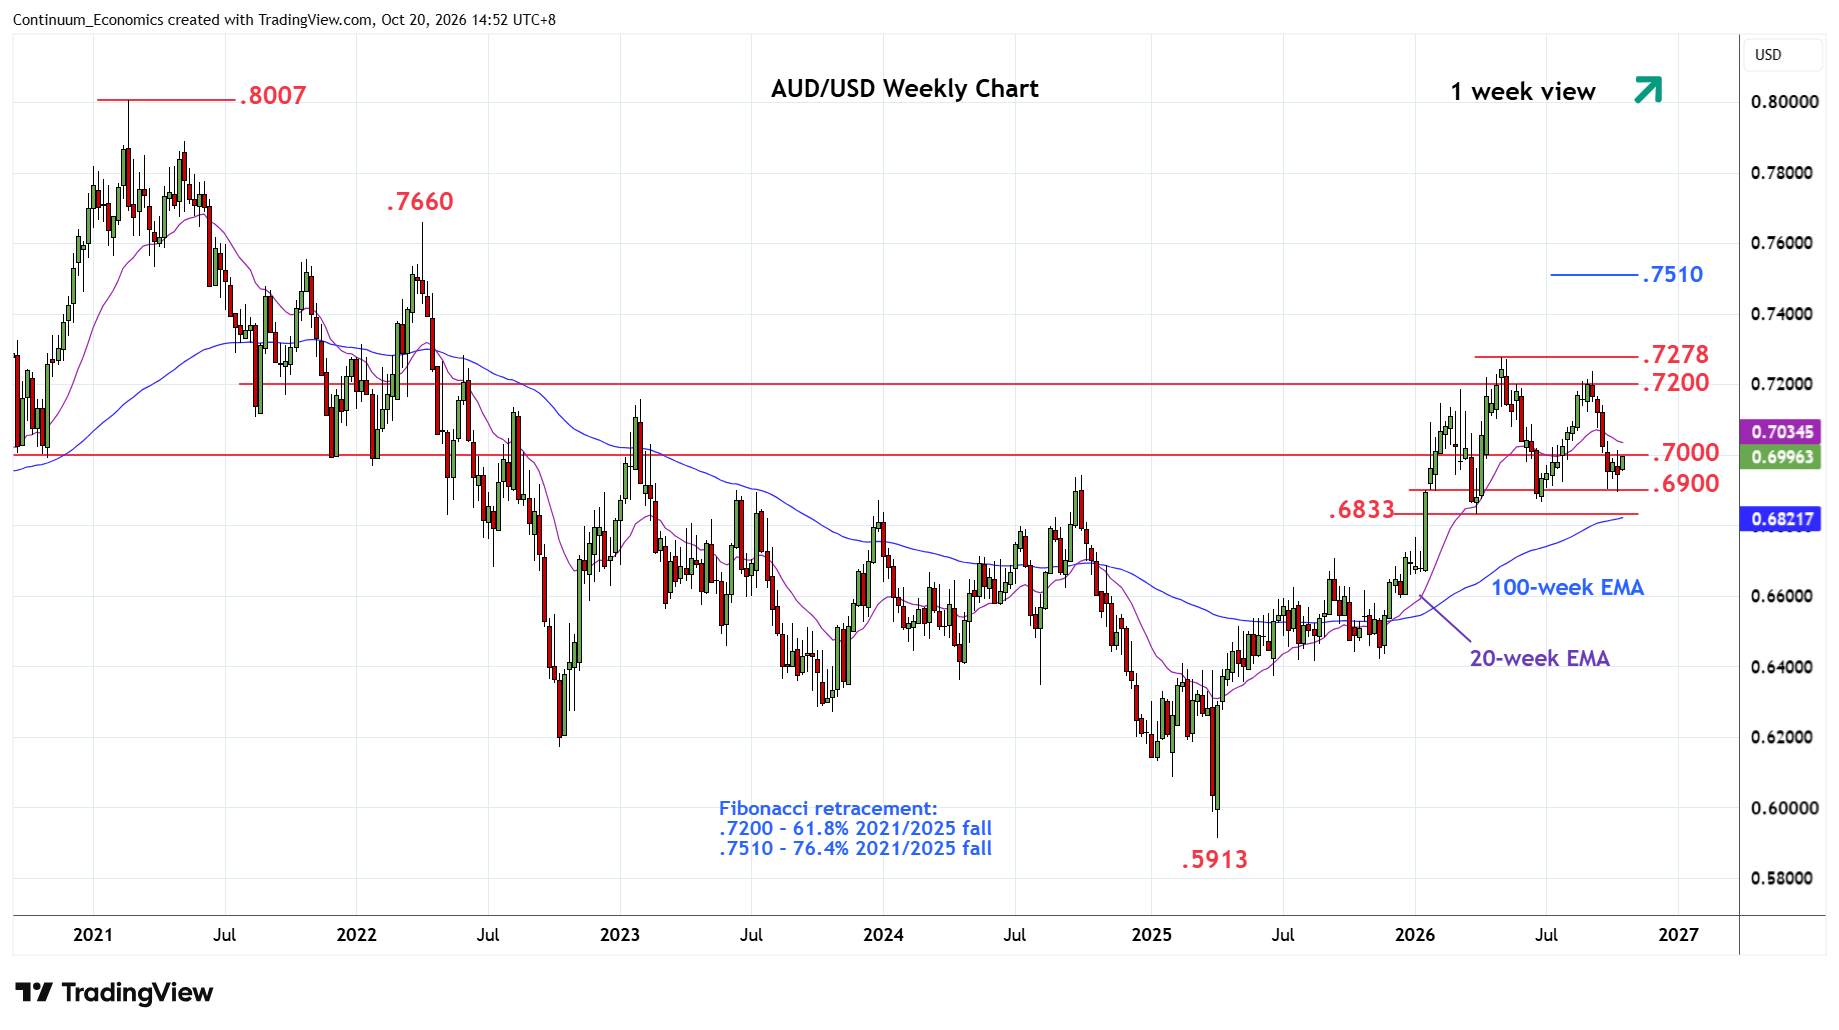
Even with the current clearly risk-laden global environment, AUD/USD continues to benefit both from the broad dollar framing (AUD was at record shorts last week on the IMM) and from shifting RBA expectations. Comments from RBA’s Hauser hinted that the RBA would be faced with grasping the nettle in terms of not protecting the labour market given it was ‘pretty clear’ that ‘materially worse’ inflation would come in above RBA forecast.
Pricing for a hike at the Nov meeting has nudged out to odds-on (55-60%) and at the moment, amid receding imminent Fed expectations, and clear risks to ECB pricing, the market is tending to reward those prone to hike at their next meetings, at least so long as wider risk sentiment does not implode. Technically, short-covering is also tending to be encouraged by the confirmed push off from a double bottom. EUR/AUD meanwhile continues to test just through major support too while, as elsewhere, not quite showing commitment to follow through. Of all the crosses though, this one perhaps less susceptible to any counter-trend corrections/squeezes given the similar recent AUD positioning/price action backdrop.
Thursday’s calendar is relatively light. The US sees initial claims which will cover the survey week for October’s non-farm payroll. September’s leading indicator follows.