Preview: Due October 15 - U.S. September PPI - Inflationary pressure still significant
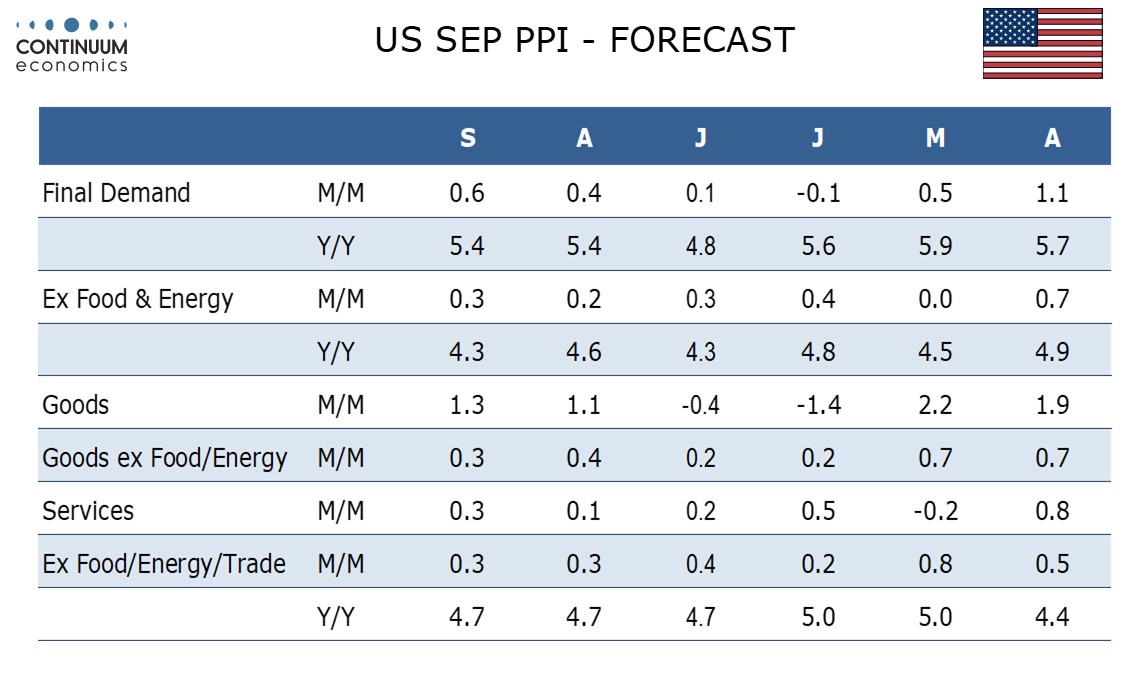
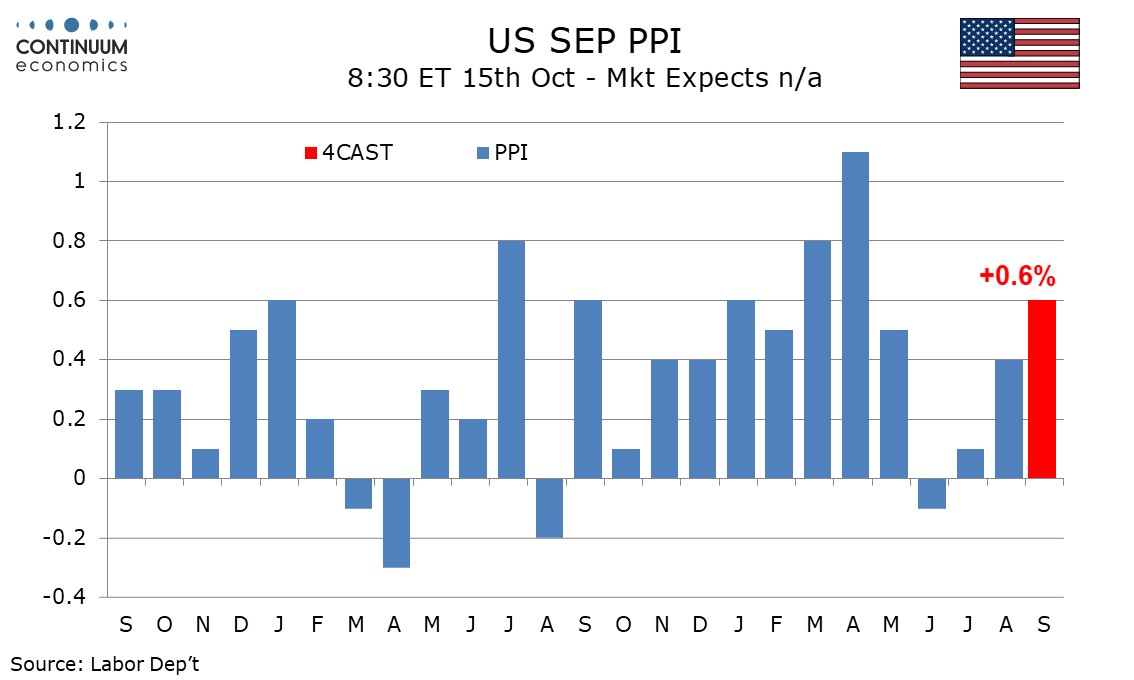
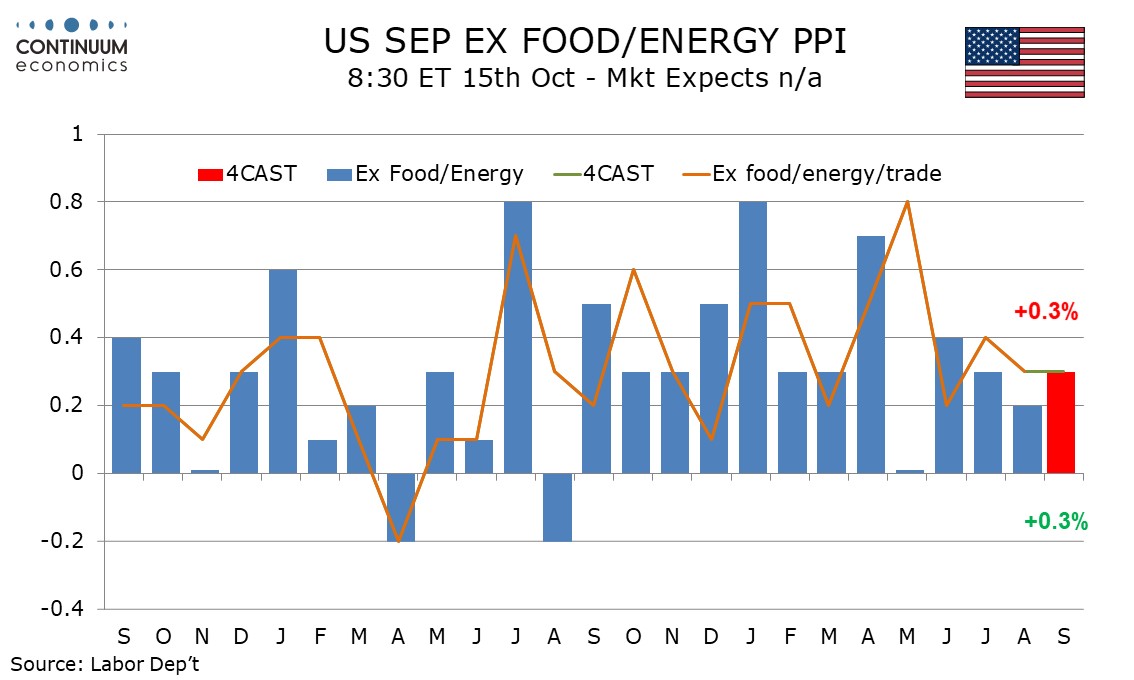
We expect September PPI to increase by 0.6% overall led by energy with 0.3% gains in both core rates, ex food and energy and ex food, energy and trade. This will suggest inflationary pressures remain elevated, with little sign of slowing at the producer level.
We expect a rise of 6.0% in energy, stronger than August’s 4.1% which saw growth resume after two straight declines. September’s strength in energy is likely to go beyond gasoline. We expect a 0.3% rise in food, a second straight modest gain after two straight steeper declines.
We expect a 0.3% rise in goods ex food and energy, slightly slower than August’s 0.4% but stronger than the 0.2% gains seen in June and July. Supply bottlenecks appear to be picking up again. We also expect services to increase by 0.3%, which would be stronger than August’s 0.1% or July’s 0.2%. Transportation and warehousing which increased by 2.3% in August is likely to remain firm influenced by the situation in the Middle East, while we expect trade prices to see a modest increase after two straight small declines. Other services are likely to be reasonably subdued, but stronger than a flat outcome in August.
We expect yr/yr growth to be unchanged at 5.4% overall but with the ex food and energy pace slowing to 4.3% from 4.6%, reversing an August bounce. Ex food, energy and trade we expect a third straight month with yr/yr growth at 4.7%. All these yr/yr paces are showing unacceptably high inflation.