U.S. September Empire State Manufacturing Survey - Some loss of momentum, prices firm
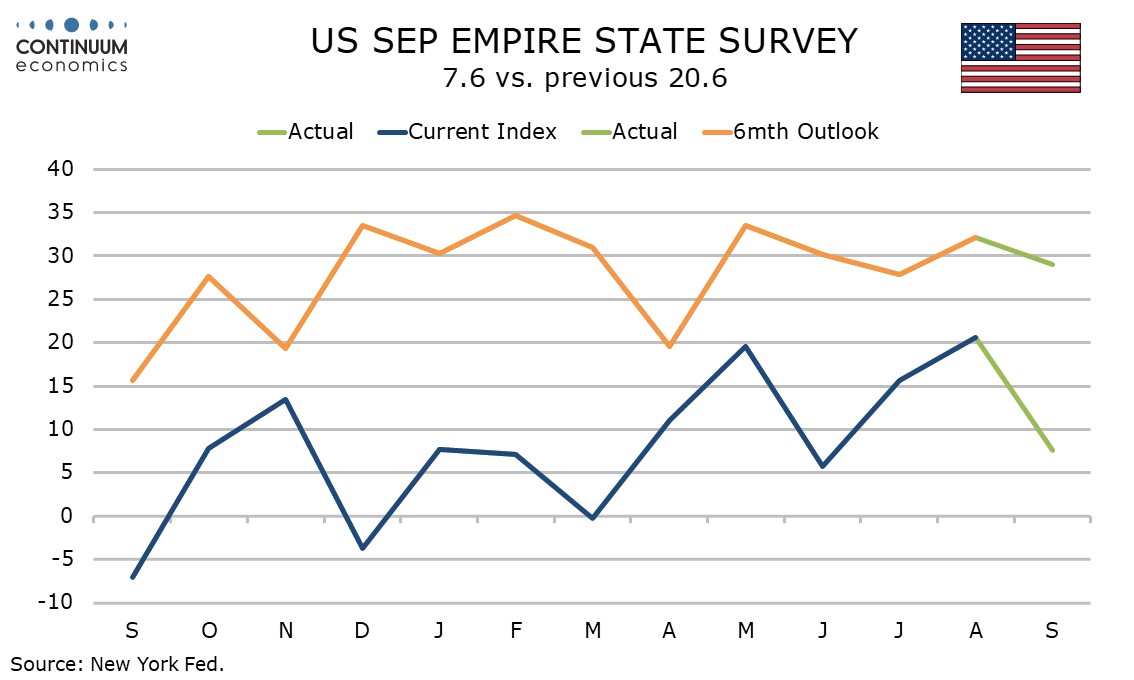
September’s Empire State manufacturing index at 7.6 is still positive but down from a very strong in August that was the strongest since December 2021. The data follows modest slowing is August’s ISM and S and P manufacturing PMIs, though both also remained clearly positive.
In August stronger data from both the Philly Fed and Empire State surveys proved misleading as signals for the ISM and S and P manufacturing PMIs, so not too much should be read into the latest data. However it may be that a recent strong business investment pace, led by AI, is stating to moderate, and that plays into recent equity worries.
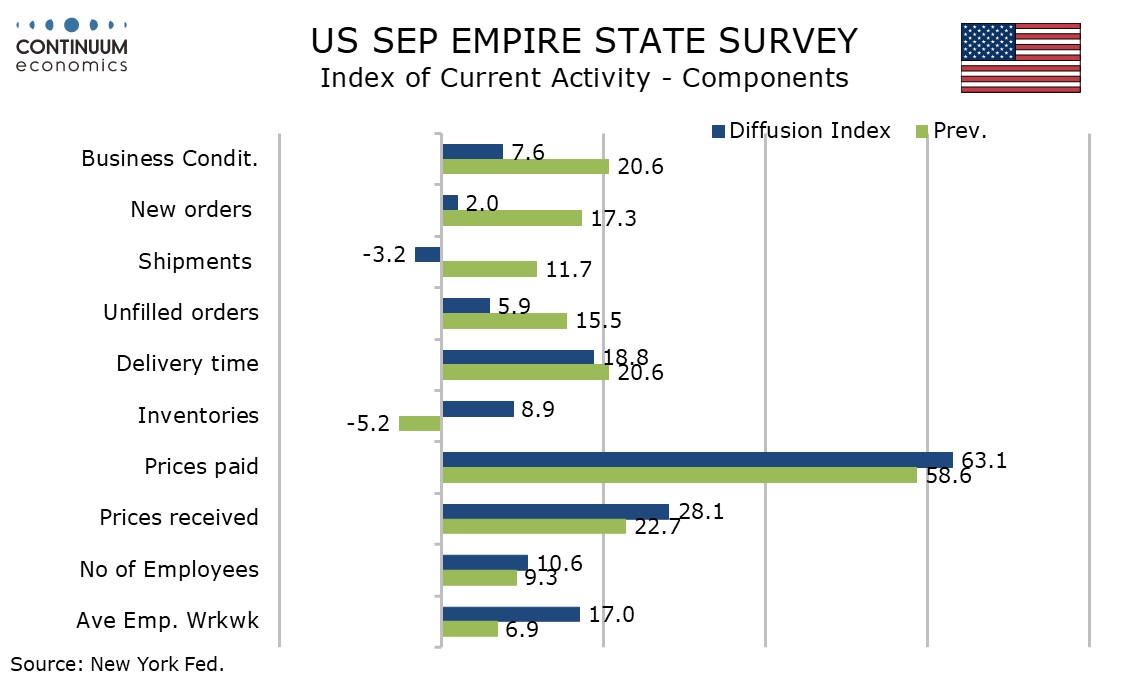
The current month data shows slowing in new orders to 2.0 from 17.3 though employment and the workweek picked up. Current month prices paid at 63.1 from 58.6 are the highest since July 2022 suggesting Middle East risks are a significant concern. Prices received at 28.1 from 22.7 are at a three month high.
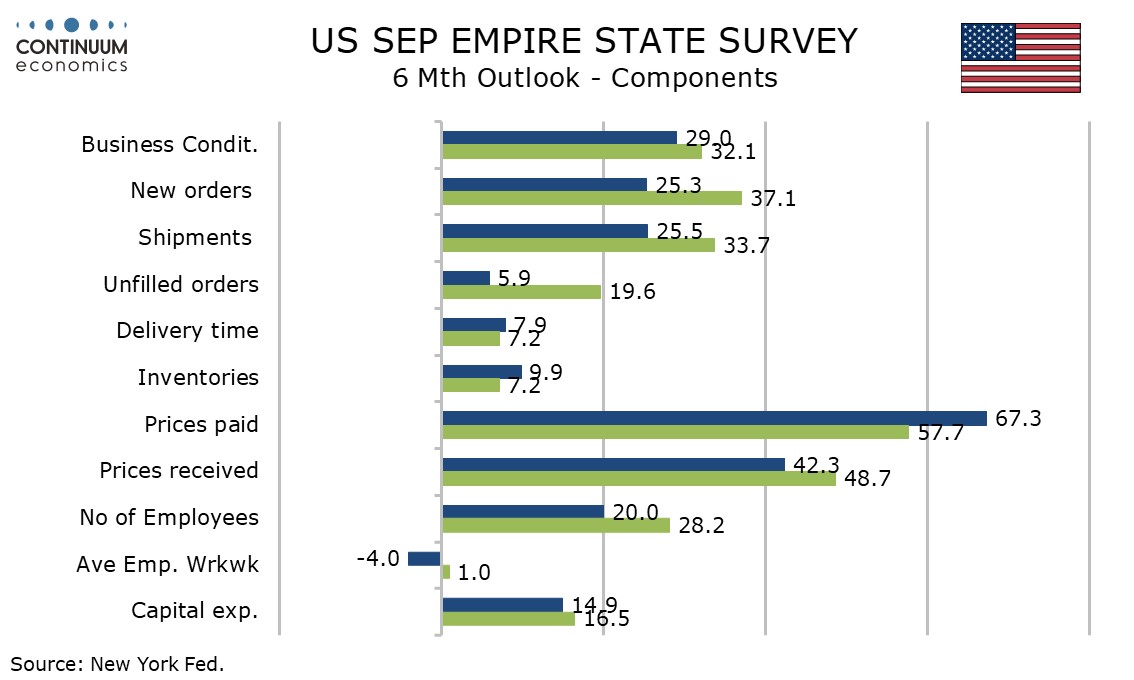
The six month expectations index for activity at 29.0 from 32.1 is slower but still above July’s 27.9 meaning this dip is not significant. Six month price expectations give a similar message to current month data, suggesting no quick fix is seen in the Middle East. Six month price expectations at 67.3 from 57.7 are the highest since June 2022. Six month expectations for prices received slowed to 42.3 from 48.7 but remain above July’s 41.9.