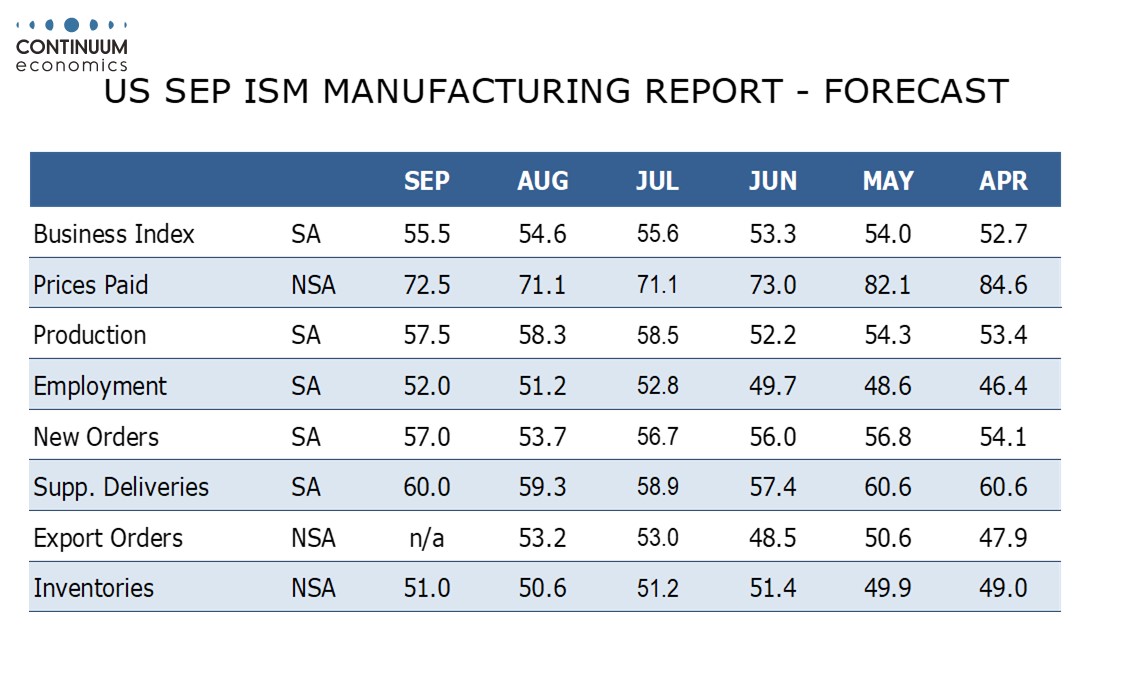
Preview: Due October 1 - U.S. September ISM Manufacturing - Back to near the recent high
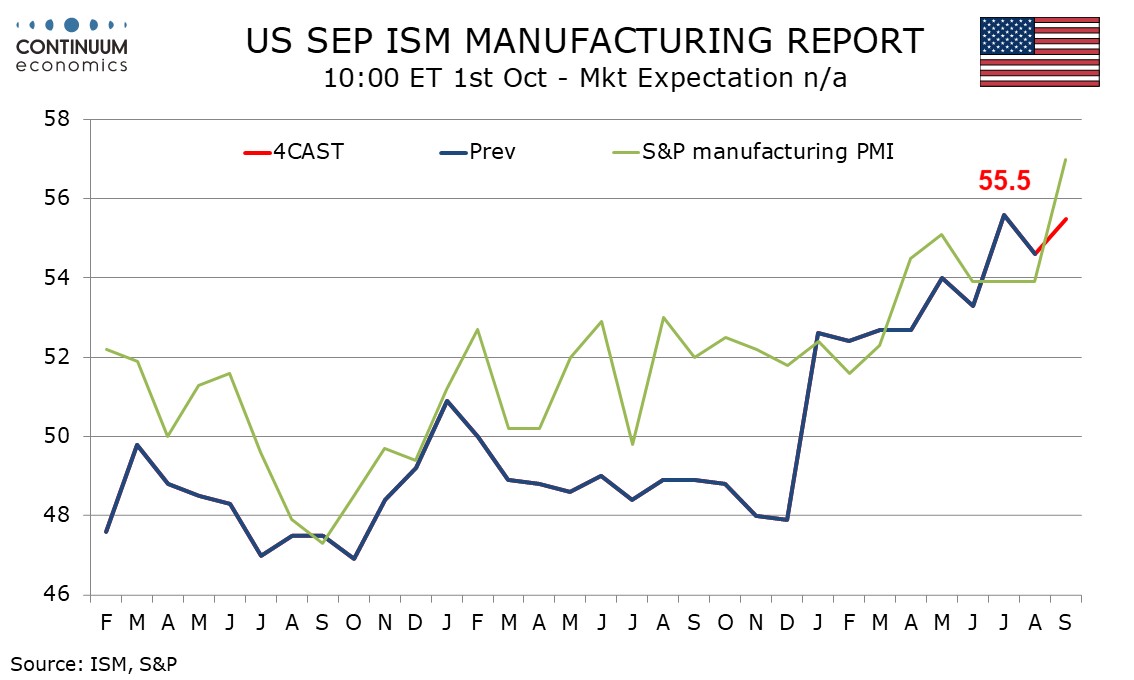
We September’s ISM manufacturing index to pick up to 55.5 from August’s 54.6, not quite reaching July’s 55.6 that was the highest since May 2022 but sustaining a clearly healthy picture.
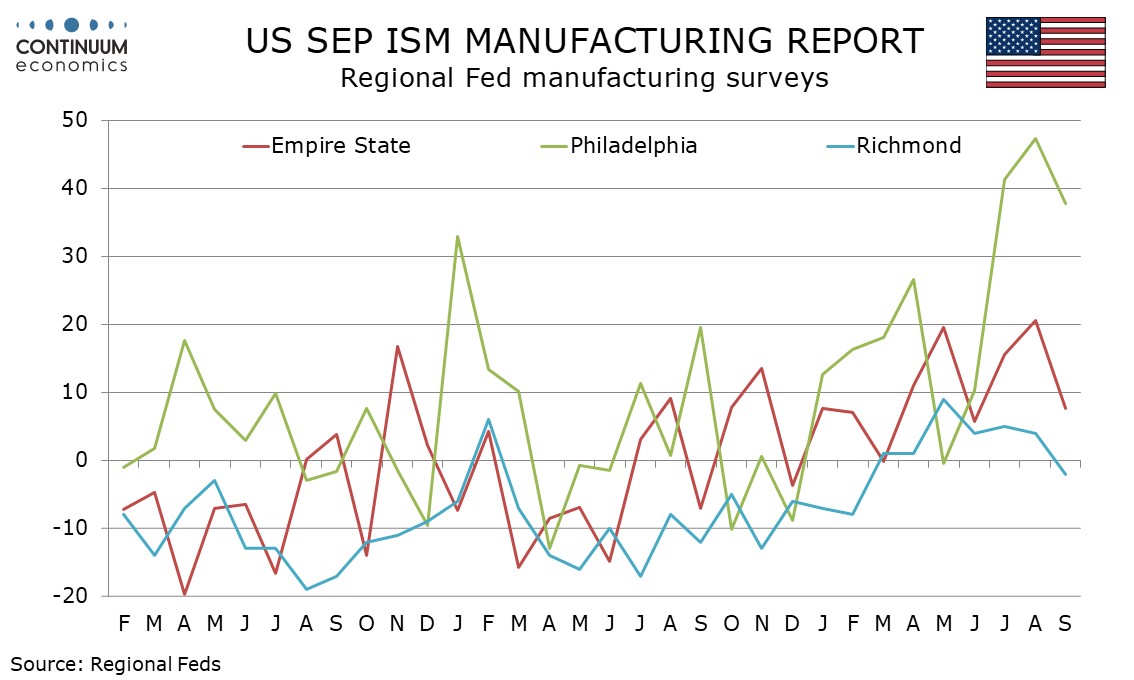
September’s S and P manufacturing PMI saw a significant bounce but in being the highest level since May 2022 does not clearly imply a fresh high for the ISM manufacturing index. Not all manufacturing surveys are improved, with the Philly Fed, Empire State and Richmond Fed indices all slower in September. The Philly Fed’s was still very strong, but the Richmond Fed’s turned negative.
We expect the rise in September’s ISM manufacturing index to be led by new orders, where we expect a bounce to 57.0 from August’s 53.7 that was the slowest since March. Production in contrast may slip from August’s strong 58.3. Manufacturing output declined in August’s industrial production report. We expect slightly firmer indices from employment, inventories and delivery times, the latter lifted by supply difficulties.
Oil prices are volatile but inflationary pressures remain elevated. We expect the prices paid index to rise to 72.5 from two straight months at 71.1, while remaining well below the recent high of 84.6 seen in April. Prices paid do not contribute to the composite.