Taking stock of France relative performance and degrees of 'contagion'
Ranking outright spreads and 3mth changes shows where credit leakage pressure is being felt to date
Souring risk sentiment across a number of fronts in recent sessions from geopolitical/oil, to tech heaviness, to of course France-led euro pressures.
Focusing on the latter front, it’s interesting to take stock of the recent trends across markets to get a sense of where ripple over has and hasn’t been felt yet.
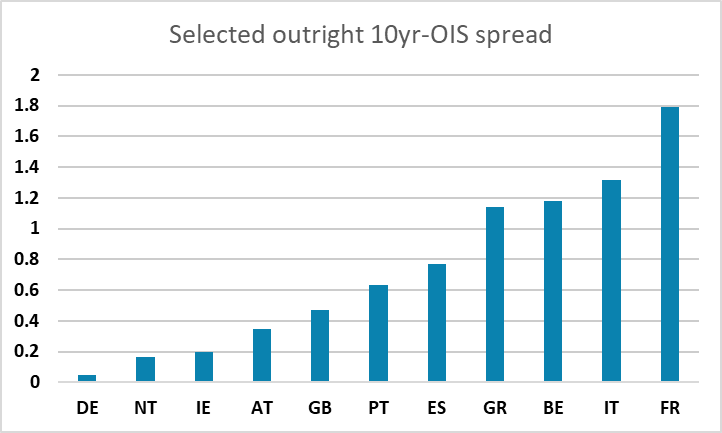
OAT spreads to 10yr OIS are the standout of course at around 180bp and with some 85-90bp of widening in the last 3 months.
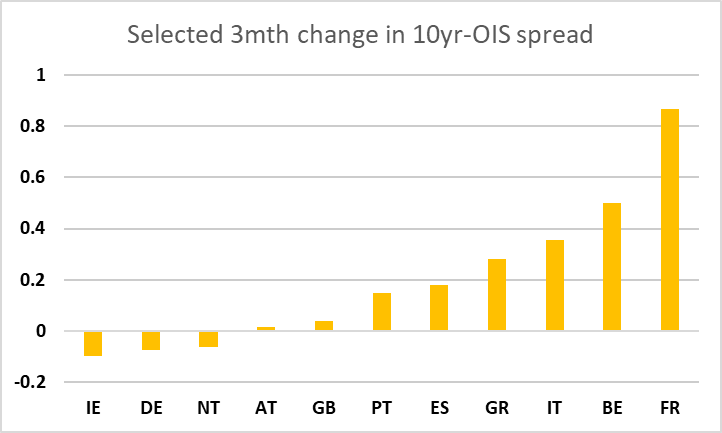
In terms of levels, that’s followed by Italy, Belgium, Greece, while in change terms its Belgium with the fastest contagion from ‘parallel’ budgetary considerations. Then scaling down in reverse contagion through partial contextual association with Italy, then Greece, with Spain and Portugal then at more contained pure mark-up and associated spillover end of the scale - while markets avoid moving fully into full panic indiscriminate exposure shedding and muscle-memory mode.
As a counterpoint, in equivalent terms, UK spreads have held pretty flat through recent months and remain in level terms just outside of core Eurozone (Swiss trades as ever well through OIS).