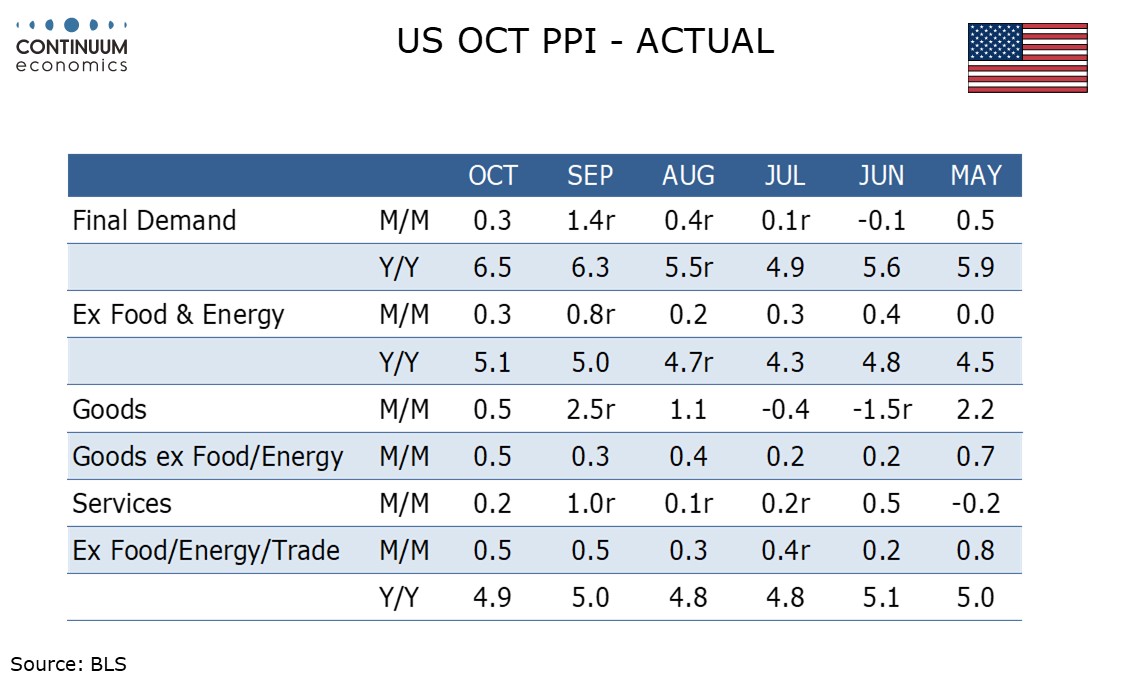
U.S. October PPI - Still firm ex food, energy and trade
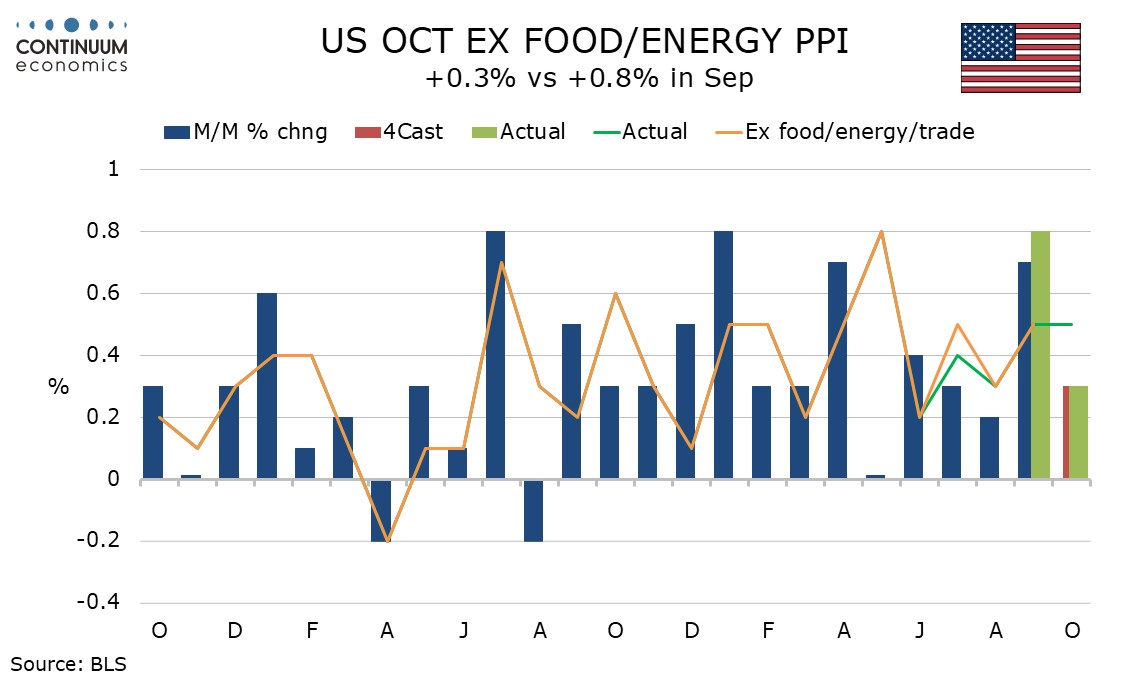
Overall October PPI is slightly softer than expected at 0.3% with a matching increase ex food and energy, this on consensus. However a 0.5% increase ex food, energy and trade suggests underlying strength, above what is acceptable to the Fed, persists.
Energy saw a pause, falling by 0.1% after a 10.0% surge in September, but food was firm at 1.3%, a second straight strong month to follow three straight declines.
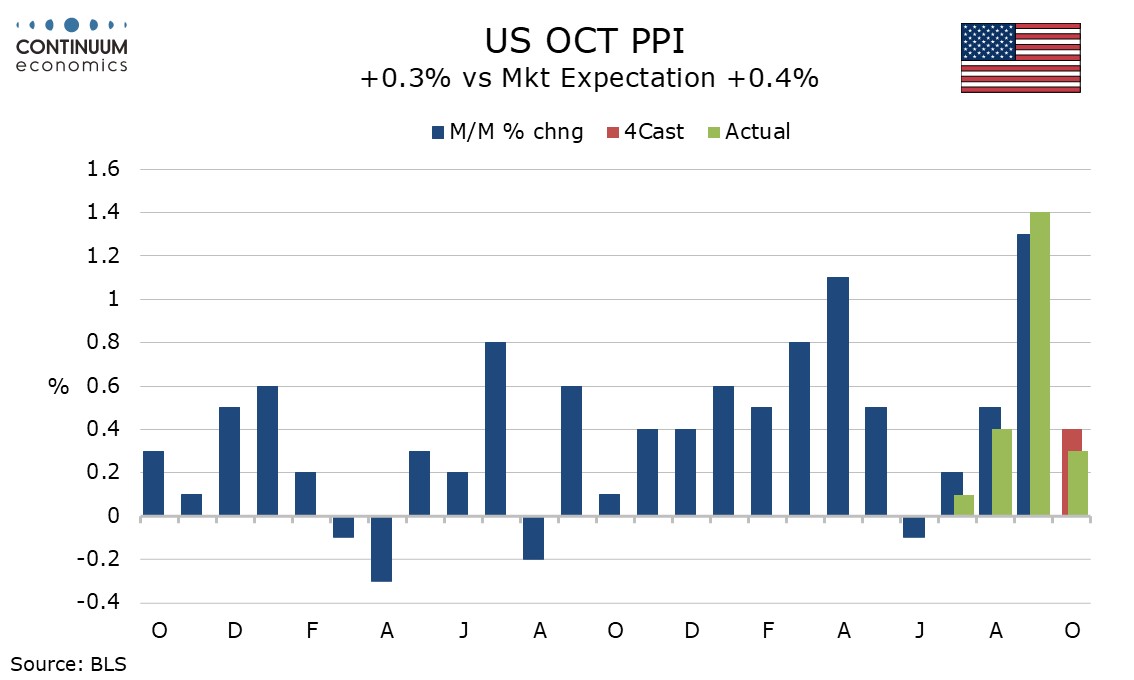
Goods ex food and energy with a 0.5% increase saw the strongest increase since May, which is troubling. Services rose by 0.2% after a 1.0% surge in September, restrained by trade prices taking a pause (falling by 0.2%) after a 2.1% surge in September. Transportation and warehousing rose by 2.0%, the slowest of three straight strong gains. This sector is sensitive to Middle East generated supply disruptions. Other services (the largest component) saw a second straight 0.2% increase. That at least is acceptably subdued but the rest of the detail is not.
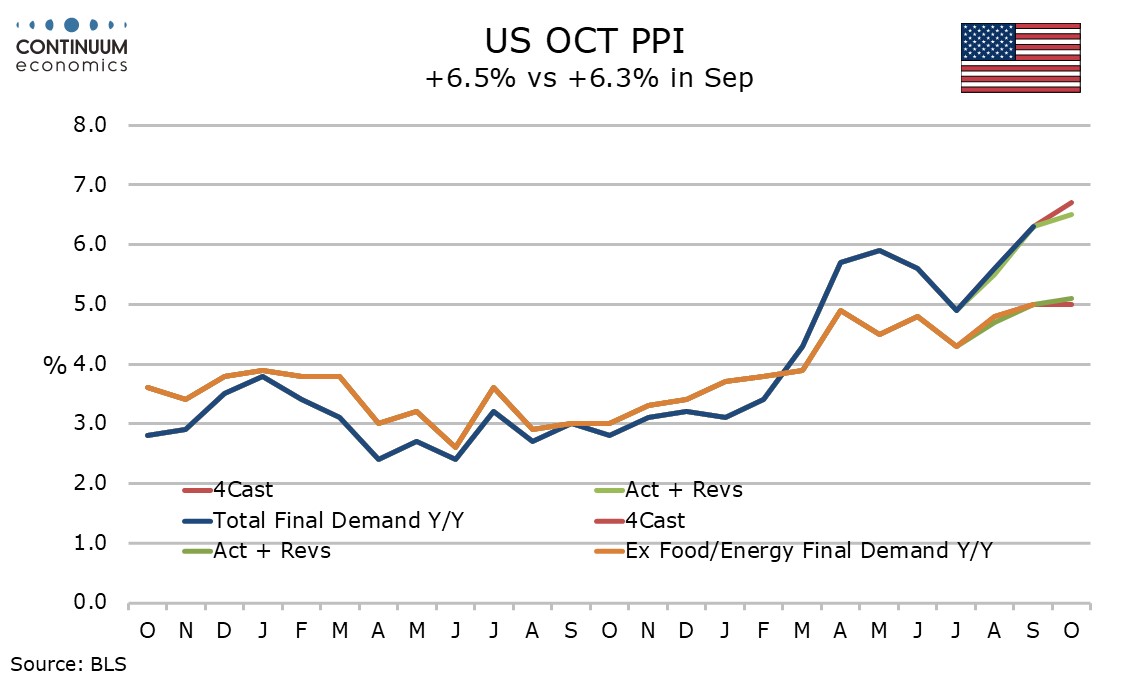
Yr/yr PPI accelerated to 6.5% from 6.3% and is the highest since December 2022. The core rates ex food and energy and ex food, energy and trade, both slipped to 4.9% from 5.0% but both have been fairly steady near a too strong 5.0% for the last six months.
Intermediate goods data was mixed but on balance mildly encouraging, restrained by dips in energy. Processed goods rose by 0.4% while unprocessed goods fell by 3.1%. Ex food and energy rates were up 0.9% and down 0.9% respectively. Intermediate services PPI however is quite worrying, up by 0.6% if largely on gains of 1.6% in trade and 1.2% in transportation and warehousing. Intermediate other services saw a moderate 0.2% increase, matching the finished data.