Preview: Due Novemeber 25 - U.S. Preliminary (Second) Estimate Q3 GDP - Even stronger
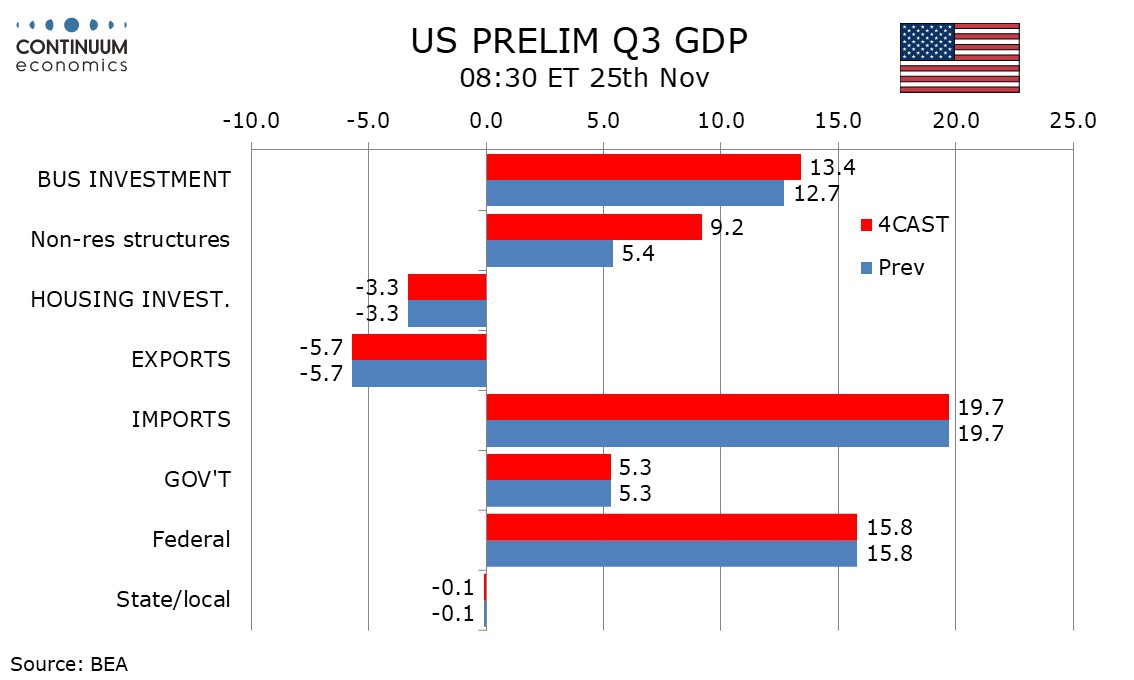
We expect the preliminary (second) estimate of Q3 GDP to be revised up to 3.6% from an already strong 3.4%, on consumer spending, non-residential construction and inventories.
October’s retail sales report saw modest upward back revisions which looked stronger ex autos and gasoline than overall. September construction spending was stronger than assumed in the advance (first) GDP estimate, primarily on private non-residential construction. We also expect a marginal upward revision to an already positive inventory contribution.
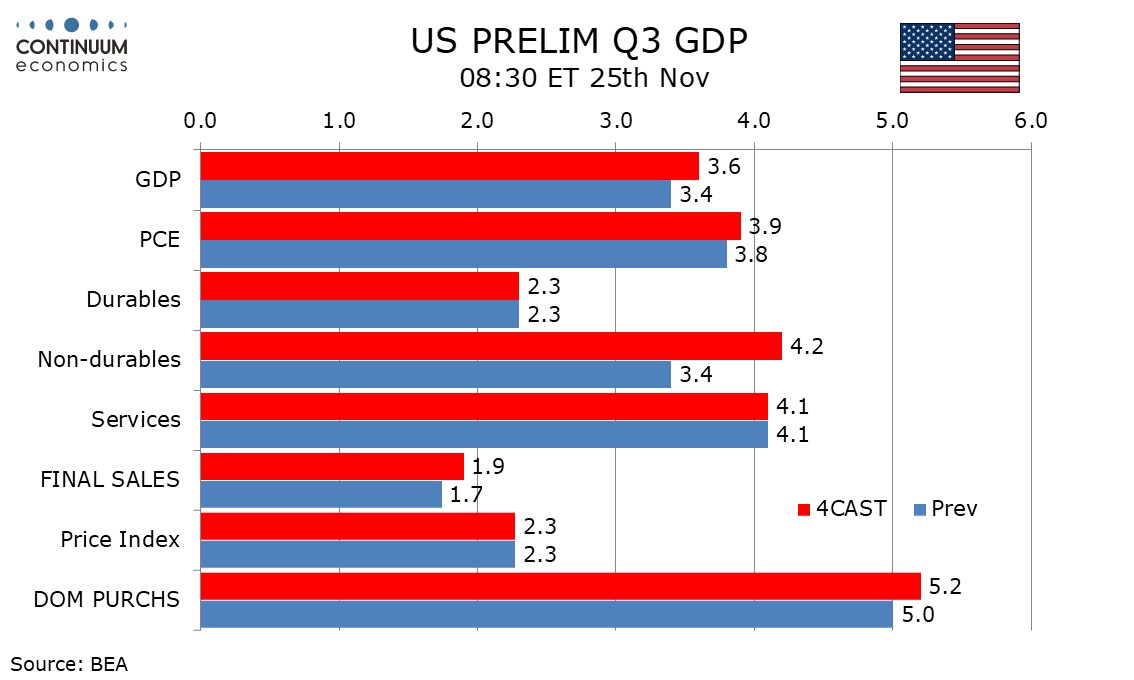
We do not expect any significant revisions elsewhere. Nor do we expect any revisions to the price indices of 2.3% for GDP, 2.1% for PCE and 2.5% for core PCE. We expect final sales (GDP less inventories) to be revised up to 1.9% from 1.7% and final sales to domestic buyers (GDP less inventories and net exports) to be revised to to an impressive 5.2% from 5.0%.