Europe Summary and Highlights 2 Oct
Dollar breather into payrolls, euro still weighed on crosses
OAT-bund still wider, if on underperformance, political development become key next few days
CHF still profit-taking/short covering with switch in focus from carry to risk avoidance
Japan CPI comes in high, EZ follows national prints; payrolls next up
Europe
Dollar takes a breather after recent fast action into the key data, though the euro more broadly remains on the heavy side.
France-Germany spread still wider, if via OAT underperformance of bund gains, 10s out to 145bp~. That’s helping to keep the euro weighed on the crosses, even as EUR/USD pauses around 1.250 having tested close to the 1.2 figure support yesterday.
EUR/CHF tests the Aug lows and USD/CHF off 30 ticks as the shift from carry to risk avoidance mood encourages ongoing profit-taking / CHF short covering on the strong runs.
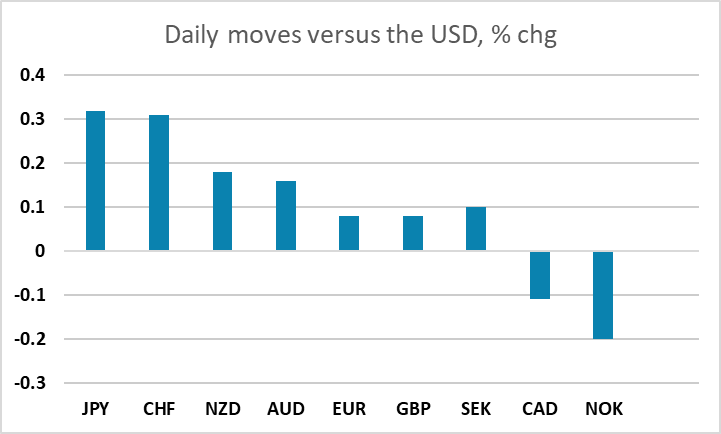
EUR/JPY also at new recent lows. USD/JPY off some 30 ticks, with a modest reaction to the strong Japan inflation data - Tokyo Sept Core CPI YY 2.7% from 1.8%, vs mkt 1.8%, adding to the case for BoJ tightening. Pair at between 2 expiry levels of 158 and 157 today with a battle for settlement out of payrolls.
EZ CPI 3.8% from 3.2% vs original consensus of 3.6%, but broadly as expected after the strong national figures. The core was 2.5% from 2.4%, as expected, so limiting any new impact.
Oil prices stay choppy - bouncing yesterday on the talk of more US military assets going to the Middle East, but off again today (Brent front month almost-$3, back to just below $100), on discussed proposal for EU to release 50mnb of diesel and IEA to release 50mn of crude.
Focus clearly turns to payrolls next, while continuing to watch French market development into and out of the weekend.