Europe Summary and Highlights 23 Oct
French PMI weakness weighs, though 1.12~ consolidation still sticky
UK retail sales weakness balanced by firmer PMI
Japan CPI confirmed higher, projection seen lifted
After a quiet overnight session, the dollar managing a bit of a bounce from oversold intraday action into the European morning, helped by soft European data, as well as slightly firmer tech risk on the session (Nasdaq +0.5%).
Japan Sep core CPI moves to 2.1%y/y, in line with market, with ex fresh food and fuel up 2.4%. Market remains priced for unchanged next month and a hike at some point over the turn of the year. USD/JPY retains its heavy tone, supply into bounces, trading sub 157.
Eurozone PMIs coming in notably weak, with the much-in-focus France down to 48.4 (mkt 50.5) from 51.1, with business expectations lowest since 2012, adding decelerating activity to the current headache. Eurozone composite 51.9 from 53.1 (mkt 52.7), lowest since June.
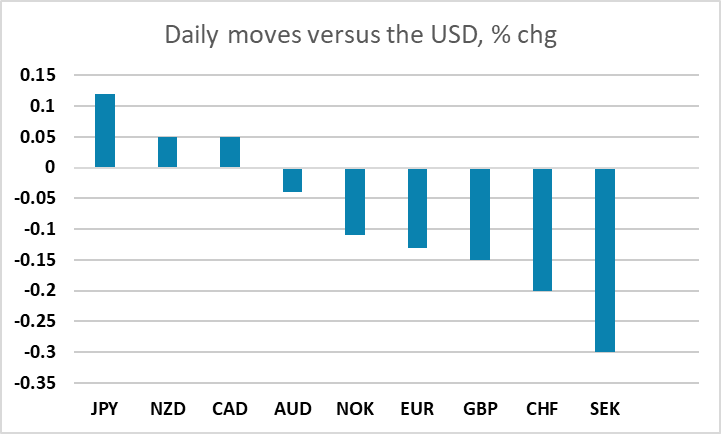
EUR/USD sees some slippage on release, though 1.12+/- consolidation still proving sticky
UK data more mixed. Some initial drag from soft retail sales, -0.4% print (mkt -0.1%) more than reversing the previous month’s 0.5% gain and taking the yr/yr rate down to 0.8%. PMIs though beat and contrast euro, composite up to 53.1 from 52.1 (mkt 51.8). EUR/GBP nets out still flat consolidating, briefly marginally stretching the recent lows.
Focus on Moody’s France review after the close, though market has been bracing in recent sessions and France is currently seeing some minor backfilling from yesterday’s spread blowout.