Europe Summary and Highlights 20 Oct
Stretched dollar longs still set backdrop; commodity currencies generally firmer, NOK lifted by oil
EUR/USD propped, but euro heavier on crosses still
UK labour mkt data supports GBP, EUR/GBP still testing lows
Stretched dollar still setting some of the background framing, helping keep EUR/USD propped around 1.220, even with the euro heavy on the crosses and OATs remaining around the wides. Antipodeans still seeing the better of the short-covering early week, while ‘oil pairs' also benefiting from pressure there (Dec Brent pushing new recent highs up 2% above $110). USD/NOK extends retracement and NOK/SEK back to stretching the highs.
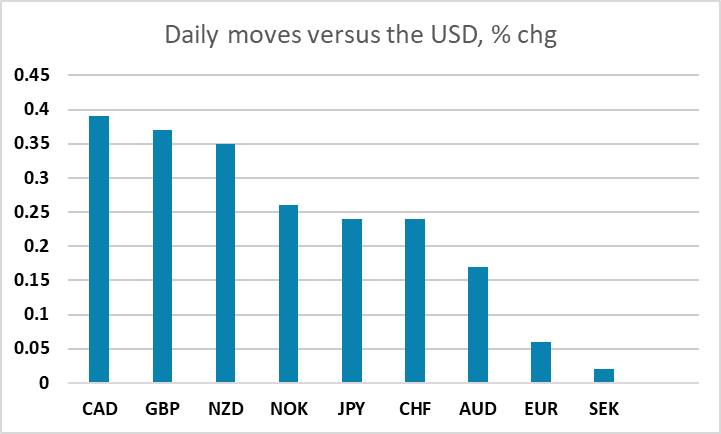
Sterling also still benefiting from short base and from better UK data, with labour market data seeing earnings ex-bonus up to 3.7% (mkt 3.6%) and HMRC payrolls up 13k in Sep, with Aug revised also to +1k from the prelim -26k (vacancies are still weak though). Data enough to go with the grain of Nov hike expectations and also with the grain of the cable lift from its recent oversold selloff, while keeping EUR/GBP pressing the 0.84~ lows.
USD/JPY steady with still better supply into any upside, sitting just on and around the 158 area. Reuters sources suggest the BoJ may slightly revise up its core CPI forecasts for FY27 this month.
German Oct ZEW 28.1 from 34.7 (mkt 30), with current conditions -35.9 from -47.1 (mkt -45)