Europe Summary and Highlights 30 Oct
Tech pressure continues out of earnings
Weighing long dollar broadly, while BoJ also supportive of the yen on the session
EZ data stays firm overall, with GDP again beating
BoJ and ongoing AI/tech pressure the main drivers in Asia and the European morning.
Japan keeps rates unchanged as expected (though unexpectedly speeds up ETF divestment, Y860bn a year from Y330bn), while increasing inflation forecasts (FY27 to 2.6% from 2.4%),
Ueda’s press conference in tune with market expectations for a follow up hike around turn of the year, noting gap between current and neutral rates, the need to adjust policy ‘proactively’ rather than passively to meet the 2% target, and that cannot ignore risks of inflation overshoot.
Plays to firmer yen, while broader FX tone driven by ongoing AI/tech pressure, with Nasdaq -2.3%, pushing below the recent range. Ongoing concerns over cash burn and net free cash, Intel and Amazon following on from Google’s big hit.
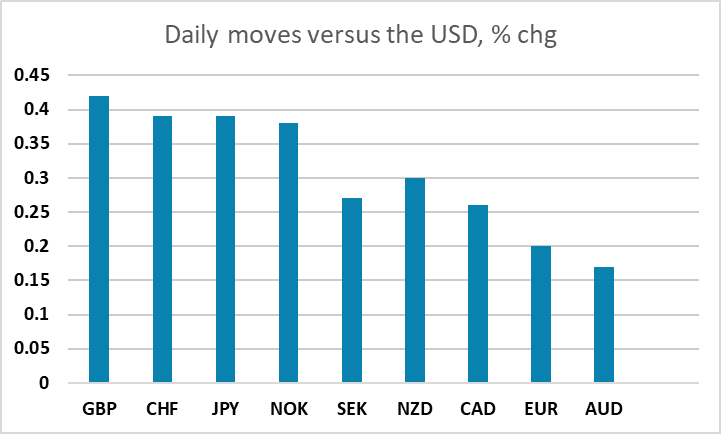
Tech weakness tending to hit US yields and the dollar, and support CHF and JPY in current context. DXY off just under ½ %. Market is long dollars and coming out the other side of the central bank positioning, so also having that covering bias, which could turn a little squeezy. EUR/USD also testing back above 1.12 to be turning the s/t technical momentum around.
EZ GDP beats expectations again at 0.4%q/q in Q3 (mkt 0.2%), Spain and Netherlands outperforming and France notably weakest at -0.1%.
For inflation data, generally firmer too - France EU-norm CPI 3.8% from 3.4% (mkt 3.6%), Italy 5.6% from 4.2% (mkt 4.6%), Spain flash HICP 4.9% from 5% (as mkt) - though German state figures coming in softer for some offset, national figures later today.