Europe Summary and Highlights 14 Oct
EUR/GBP nudges lows, politics/fiscal sentiment still tipping back to the UK, even as BoE sceptical over tightening priced in
AUD/USD enjoys technical bounce from good support
Yields remain off highs, USD levels as market waits for US CPI prints
A little bit of dollar trimming follow-through initially, with AUD/USD in particular extending its corrective bounce from strong support to regain the 0.70~ figure into the key US data. Fed William’s comments late yesterday (sees no hikes next year) did help the US yield / USD consolidation moves. US10s treading water today ahead of the CPI prints. European morning levelling out however into the key data, given wariness over upside data risks too.
Scepticism over tightening priced into next year also echoed by BoE Chief Economist Pill this morning ('Is it obvious that we will need to move, follow market pricing to four 25 basis-point hikes and so forth? So there, I would be a little bit more sceptical').
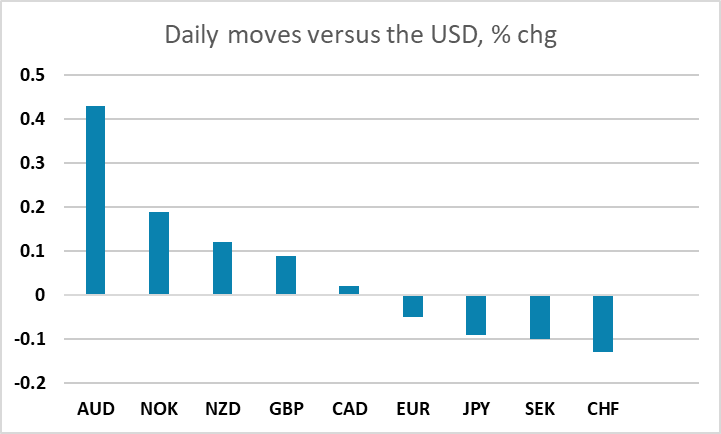
Sterling still on a generally firmer footing even so. FT suggests those familiar with matter see UK Budget funding any cost-of-living support / giveaways from tax/reductions rather than increased borrowing, although the fiscal rule headroom contingency will be eroded as an Iran buffer. IMF was broadly supported of the UK’s current course yesterday.
The budget debate and amendment process continue in France. ECB’s Lagarde backed off any hints of any near-term support saying ‘the primary and first solution lies at home’ on the fiscal front.
FT interview with Le Pen not terribly helpful either – vows ‘trial of strength’ with EU, and still campaigning on basis of cutting French contributions, and ECB to finance investments from energy to defence.
EUR/GBP continues to grind lows amid the shifting relative fiscal/political risk sentiment.