Europe Summary and Highlights 2 Nov
Another bounce-Monday, some corrective action early week, not quite yet a squeeze
Oil off sharply on reports of talks, highlighting NOK's exposure to such less-factored-in scenarios
A slight echo of last Monday as we start off with a bit of corrective/covering vibe, not quite turning fully into a squeeze yet. EUR/USD has recouped 1.12, alongside the bounce in tech stocks and with oil off and France spreads making less ‘noise’ (resting off the highs in the 160 region). USD/JPY also testing back into recent supply up to 158.
Nasdaq +0.8% ahead of Apple earnings, albeit only back up towards a re-test of last week's range break rather than back to stable.
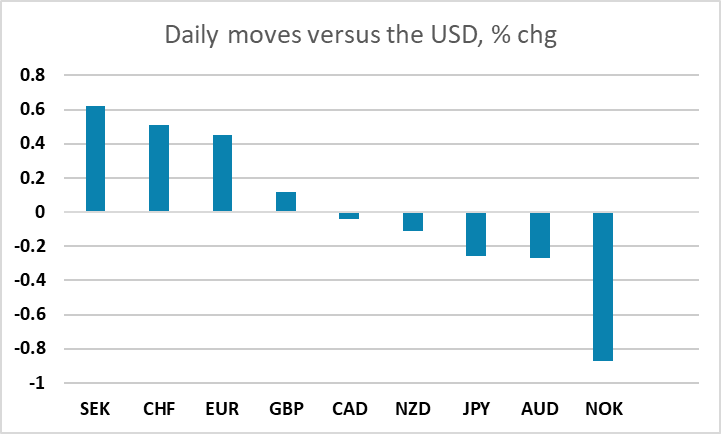
Oil has front months down a chunky $4 – 4 ½ on the back of reports that talks between Iran and Qatari mediators extend into a third day, with a proposal being discussed that would open the Strait in two days of an agreement with the US. Nymex looking back below $100.
Some reciprocal action on the FX side, which also extends to session pressure on the NOK, that is particularly exposed to liquidation in the event that a surprise positive scenario played out – US has seemingly been initiating more positively here of late, enmeshed too with US and Israel domestic politics. NOK/SEK and EUR/NOK both with 1%+ moves.
Just final PMIs on the data side. EZ manufacturing revised to 52.7 from 52.4, UK stays at 52.8