Europe Summary and Highlights 29 Sep
AUD sells fact out of RBA hike
Dollar retains broad bid, EUR/USD stretches for June lows
USD/JPY still comparatively capped out of yesterday's verbals
Europe
RBA delivered the expected hike and retained a conditional tightening bias (continue to do what it considers necessary to bring inflation sustainably back to target, including increasing the cash rate target further if needed). The market already had 1 ½ hikes priced in prior though, and Nov follow up hike odds actually ebbed a touch as Bullock struck a more balanced note. AUD sees a little ‘sell the fact’, with the grain of the heavy action prior, off around 30-40 ticks vs USD and NZD.
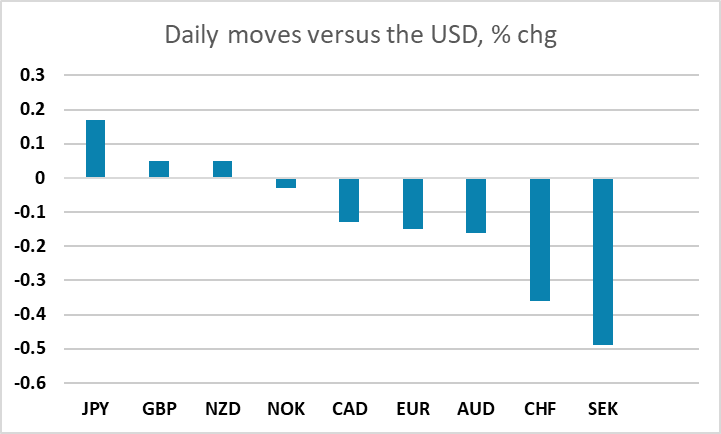
Dollar retains it broader bid tone across the board too, with technicals and momentum still supportive, even if stretched. EUR/USD extends -0.4% to 1.3330s, to close in on the 1.1324 low from June. US yields still at and around the highs across the curve. Squeeze/increasing profit-taking on USD/NOK also continues.
USD/JPY retains some capping after yesterday’s verbal intervention, keeping yen crosses towards the recent lows. Some focus on whether month end also sees some possible USD/JPY selling.
Spain flash HICP 5% from 4.6% vs mkt 4.9%. EZ economic sentiment 97.9 from 98.4 vs mkt 99.