Europe Summary and Highlights 30 Sep
USD/JPY, yen crosses, dip on period-end yen demand, before paring
AUD still easing back, CPI slightly below mkt
GBP trying to base, upward GDP revision helps
EZ national CPI measures coming in high, supporting hike bets, though still skew to Dec over Sep
Europe
Period end (FY-half) demand lifts the yen overnight, with a USD/JPY low of 156.35, and new lows on crosses, dropping through the Tokyo fix, before paring. Pair back to 157, where options expiries are today.
Australia CPI comes in below market, trimmed mean 0.2% vs mkt 0.3%, albeit 3.6%y/y as expected. Goes with the grain of the corrective tone continuing through the RBA, AUD/NZD off 40-50 ticks.
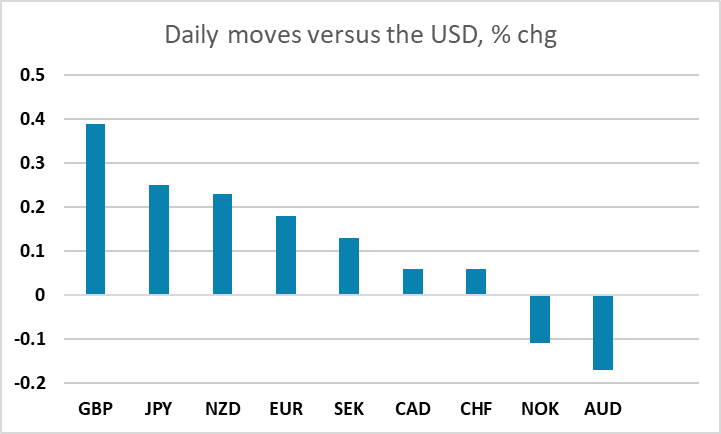
UK Q2 GDP revised up to 0.5%q/q from 0.4%, and 1.4%y/y from 1.2%, bolstered by strong business investment. Sterling continues to try and base out, cable up 30 ticks. EUR/GBP easing back further from the failed 0.86 test, back to 0.8550~.
Eurozone national inflation figures continue to come in strong. France up to 3.4% vs mkt 3.1%, Italy 4.1% from 3.2% vs mkt 3.8%, German state figures typically accelerating by 0.3 to 0.5pp, a sharper pick up than the consensus for the national figure due later today (mkt consensus for CPI 3.1% from 2.9%, with HICP 3.2% from 2.9%). ECB Oct odds nudge back to around 40%, albeit with Lagarde’s earlier week ‘measured response’ comments still tending to keep the market leaning to Dec.