Europe Summary and Highlights 25 Sep
USD/JPY trims, FinMIn Katayama advertises Trump's concern at yen weakness
Bonds, dollar steady in the morning after rapid run
Cable offered touch of support from recent BoE comments lifting Nov hike odds
Oil trims as US-Iran talks continue, market not overly convinced of anything soon
Europe
USD/JPY sees some capping back after fast run, around - ½ % to 158~, as Japan FinMIn Katayama suggests Trump at UN side line talks expressed concern about the yen's weakness and suggested that an undervalued yen is problematic.
Otherwise some current levelling out in the morning for bonds and dollar from rapid moves.
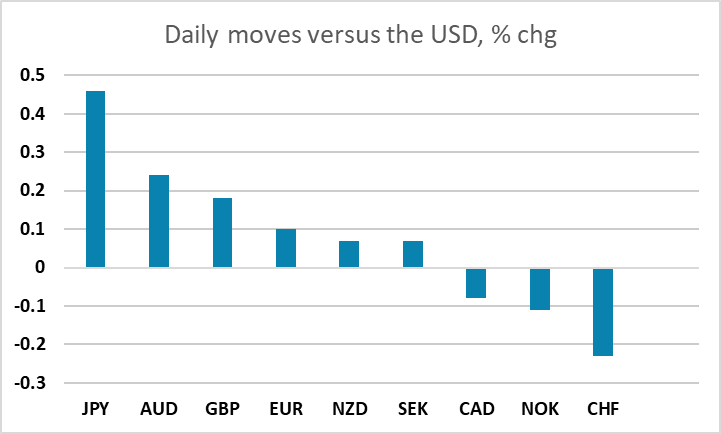
Cable steadies a little off the 1.32~ support. Recent comments last few sessions (Breeden, Lombardelli) hint of a November hike unless sudden energy backdrop change. Market pricing up to 70% now. That said, comments all frame it in context of current rates starting higher and a move rather than necessarily a cycle (“For me now, the question is: 'Do we need to do the first move?' Whether or not we need to do many more I think depends…”).
BoE's Bailey speaking this morning offers a similar line, while noting subdued pass through and mortgage rates: 'We haven't increased Bank Rate. It's going to get harder to maintain that stance the longer we have high energy prices'.
Brent off just under $2, though still well off its week lows, waiting for development. Suggestions that US-Iran are said to be exploring a phased deal but market many-times-bitten sceptical this is progressing fast, given Iran demands and apparent US lack of pre-election urgency.
EZ M3 growth 3.5% from 3.4% (mkt 3.5%). German GfK consumer sentiment -30.6 from -26.8 (mkt -27.4)