Europe Summary and Highlights 28 Oct
Dollar holds onto its firmer position into central bank events
Kiwi the big mover, knocked back after surprise hold
Expected strong AUD CPI helps amplify the AUD/NZD lift to highs
Relatively subdued pre-FOMC Asia and European morning with the big exception of NZD. Cable does continue to lean a little lower into the UK Budget, as some recent longs pare back into the event risk.
Big mover the kiwi, though with NZD/USD spiking back down towards the mid Oct base before settling on 0.56~, while AUD/NZD up to fresh highs through 1.25. RBNZ split-decision hold was a big surprise with a hike largely priced in, even if Breman did highlight upward revision to OCR projection and upside risks discussed, along with NZD weakness.
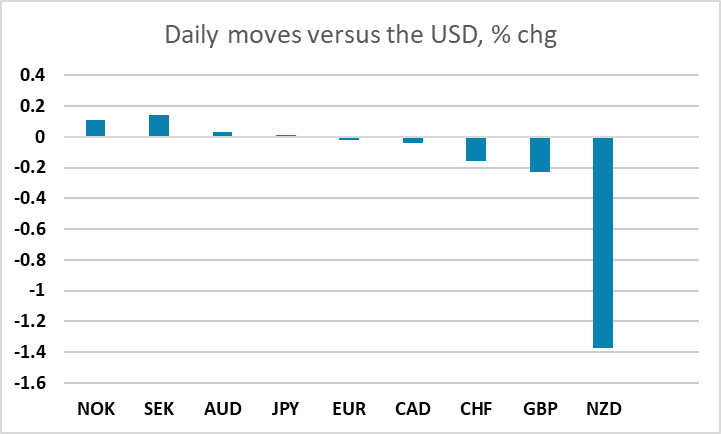
On the flip side, Australian Q3 CPI does come in strong, if broadly as expected, at 1% trimmed mean (weighted a fraction lower). Hike probably for next meeting up at around 85%, and goes with the grain of the antipodean cross move on the session.